
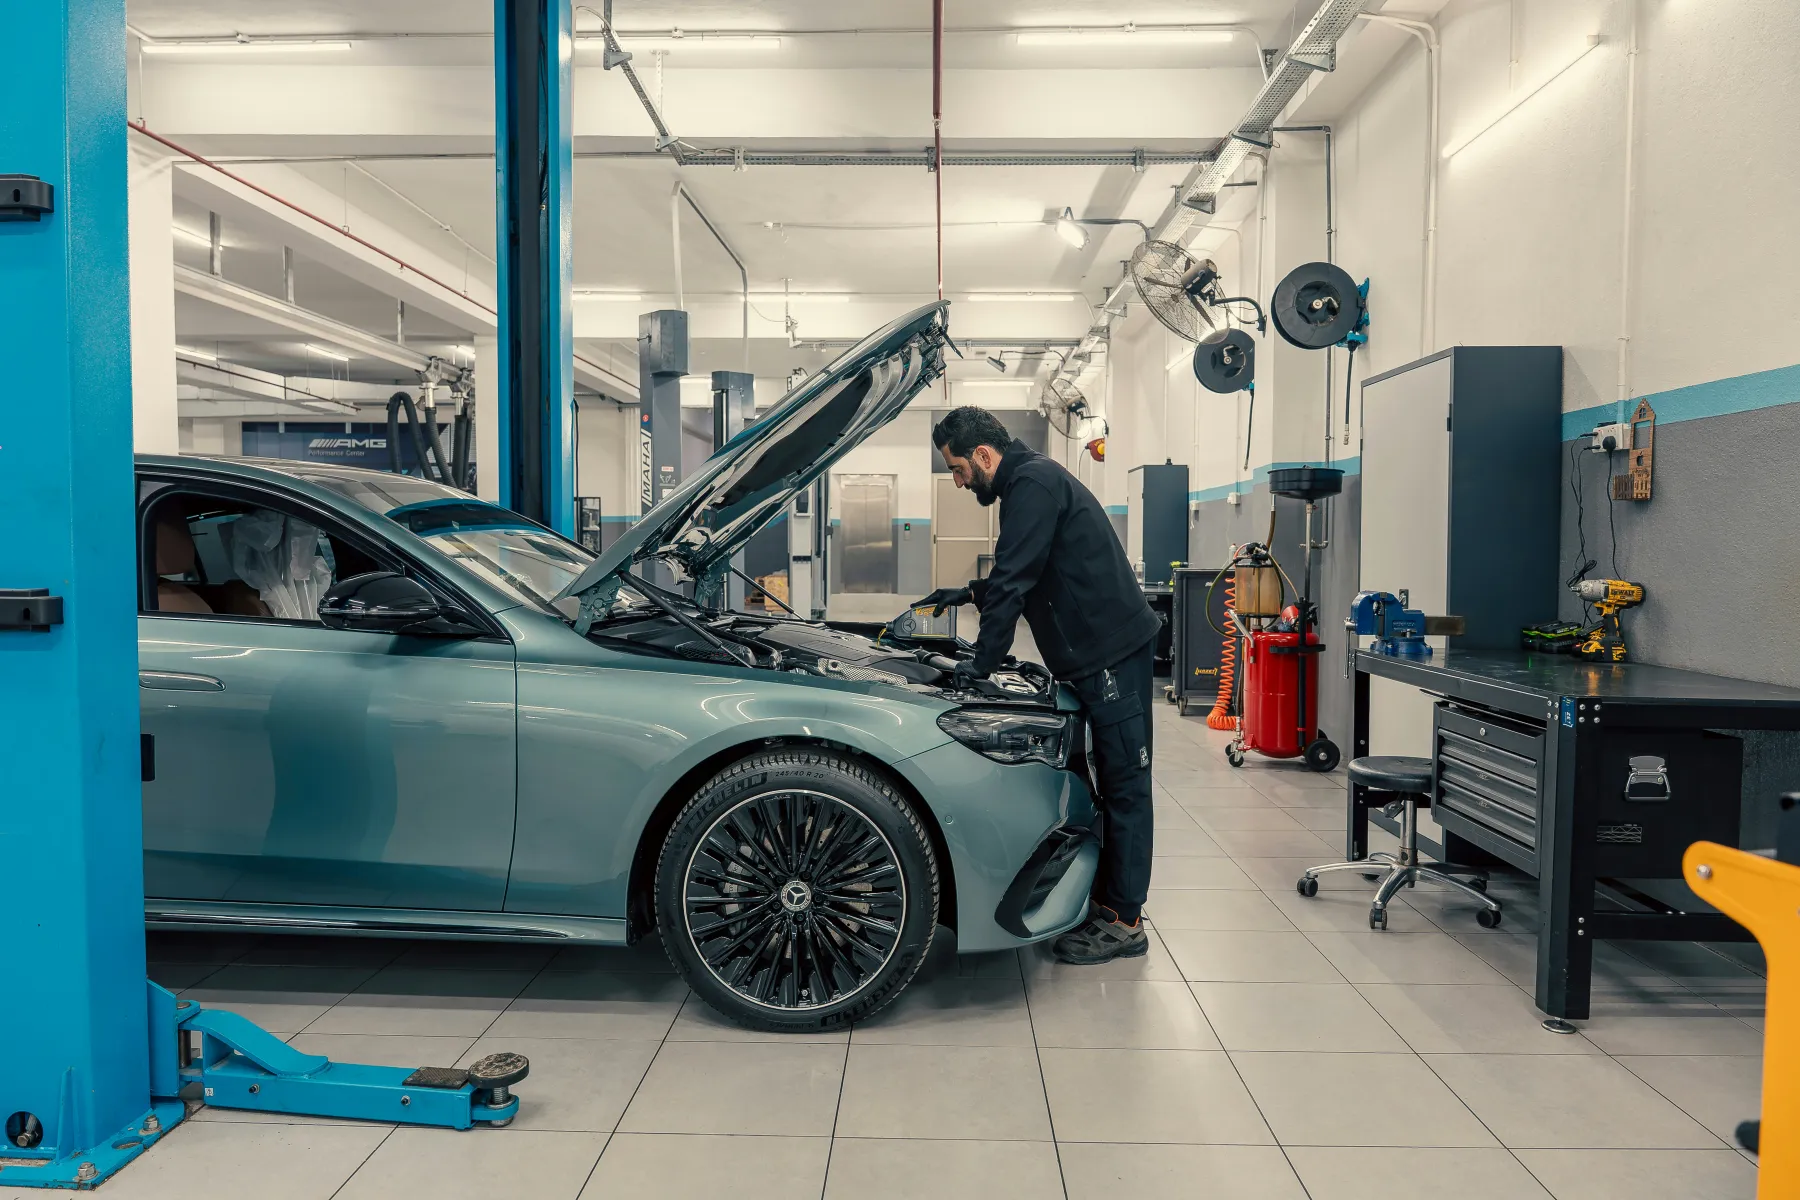
Auto Repair Business Loans and Financing: Lifts, Diagnostics, Parts and Payroll
Working capital for payroll and parts, and equipment financing for lifts and diagnostics.
Soft credit pull only, no obligation
- Same-day decisions
- from some providers
- Subject to provider approval and document turnaround.
- 700+
- industries served
- Reviews
- Fleet job done
- Invoice sent
- Fleet account pays
Net terms
Rates, factor rates, fees and terms are set by the funding provider that makes your offer and are disclosed in that provider's agreement. Figures on this page are illustrative ranges from providers in our network, not offers.
The structure that fits first
- Lead productWorking capital
Sized from card settlements and fleet deposits; covers payroll, parts and a slow month
Providers size it from the card settlements and fleet-account payments landing in your business account, which is the clearest revenue signal in this trade.
working capital for auto repair shops - Equipment financing
Lifts, alignment racks, tire machines and diagnostics: the machine secures the deal
For a lift, an alignment rack, a scan tool or a tire machine, equipment financing for auto repair shops lets the machine secure the deal and keeps your cash where it is.
equipment financing for auto repair shops - Business line of credit
Parts inventory and a fleet-account gap that reappears every month, drawn and redrawn
Parts inventory that turns over month after month is usually a business line of credit problem rather than a lump-sum one: draw, repay, draw again.
business line of credit
Decisions from some providers the same day, depending on the provider.Subject to provider approval and document turnaround.
The numbers before you apply
Typical amount
$10K–$10M
Across the products in our network
Equipment amounts
Up to $5M
Up to $500K on the application alone; up to $5M with full documentation
Speed
As fast as 6 hours
Same-day decisions from some providers; funding as fast as 6 hours, subject to provider approval and document turnaround
Amounts considered by providers in our network, depending on the funding provider. Not an offer. Cost is stated on each product page.
What do auto repair businesses use financing for?
Five needs cover most applications from this industry, and four of them pay for themselves out of bay time. A sixth, less common one: buying the shop, the building or a car wash. That is an acquisition, and it belongs on a longer schedule than anything else on this list.
Bay equipment
Heavy-duty lifts, alignment racks, tire changers, balancers, A/C machines, brake lathes.
More: Bay equipment
A scan tool counts too. Equipment is the clearest case in the trade: a second lift is a second bay, and a second bay is revenue you can measure.
Diagnostic software
Subscriptions, OEM licenses and training. Newer vehicles are why shops turn work away.
More: Diagnostic software
The fix is a capability purchase rather than a repair.
Parts inventory
Common wear items bought ahead, so a car does not sit in a bay waiting on a delivery.
More: Parts inventory
This recurs every month, which is why it suits standby capital better than a lump sum.
Payroll and hiring
A new technician is paid in full for months before the billable hours catch up.
More: Payroll and hiring
A good one is hired when available, not when it is convenient.
Slow fleet accounts
Fleet and commercial work is good work on net terms: reliable invoices, late cash.
More: Slow fleet accounts
The gap between the two is a working capital gap.
What do providers look for in an auto repair file?
Deposit consistency
Revenue in every month of statements counts for more than one strong month followed by a weak one.
More: Deposit consistency
Card settlements and fleet-account ACH read best, because they are verifiable without any extra document.
Share of revenue in cash
A shop that takes much of its work in cash is harder to size: a provider can only underwrite what reaches the bank.
More: Share of revenue in cash
If your statements understate your business, expect a smaller first amount than the shop deserves.
Negative days and overdrafts
Negative days and overdrafts often get a file reduced or declined, and so does financing already in repayment.
More: Negative days and overdrafts
Existing positions reduce what a provider will add, and some providers decline stacked files outright.
Complete statements
Partial months, missing pages and screenshots stall a file longer than any other document problem.
More: Complete statements
Most providers ask for three months of bank statements plus a government ID; larger amounts and loan structures also need tax returns or financial statements.
Worked example
A two-bay independent shop turns away alignment work and heavy-duty jobs it has no lift for. It adds a third bay. One application, two structures.
Equipment financing
$85,000
A heavy-duty lift, an alignment rack and a scan tool
The machines secure the deal
Working capital
$35,000
Parts inventory and a technician's first months
Illustrative example, not an offer. Amounts, costs and schedules are set by the funding provider that makes your offer and are disclosed in that provider's agreement. Financed equipment may qualify for a depreciation deduction — consult a tax advisor.
Repair and service, body, tire, car wash — and why dealers are different
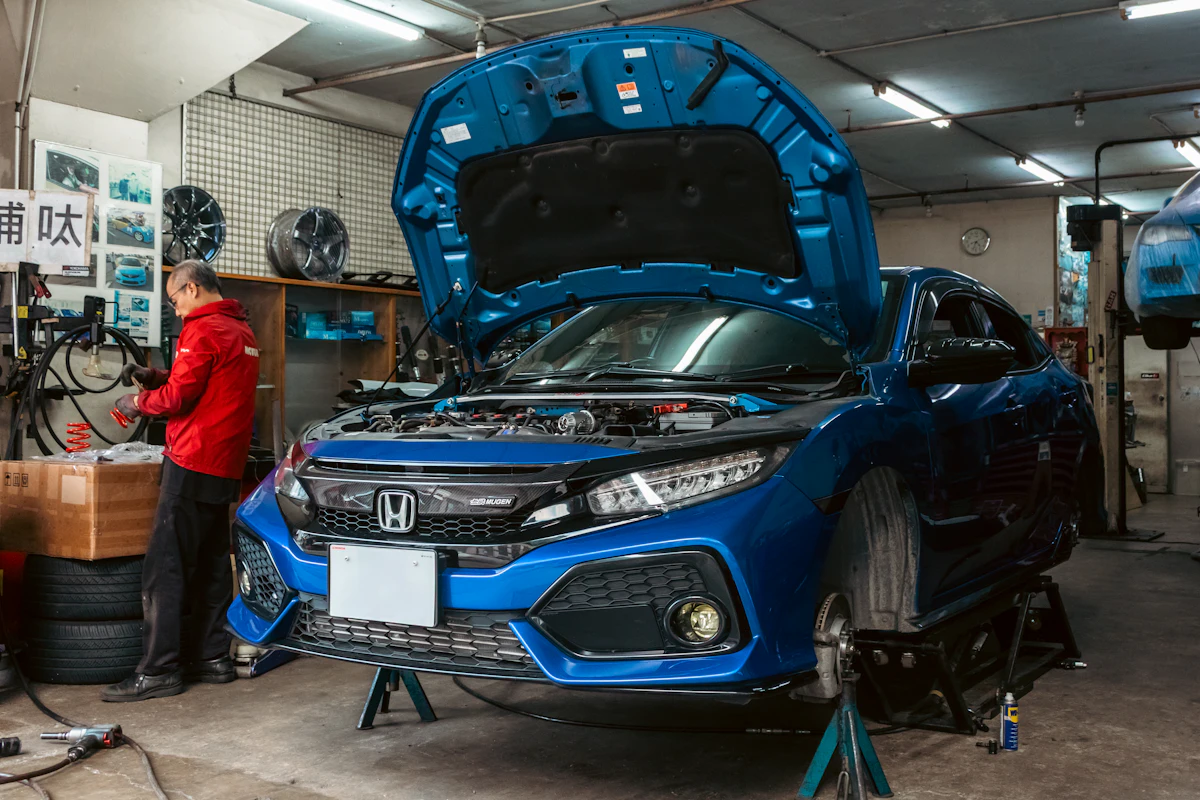
Independent repair shops
The core file, easiest to place: card and fleet revenue, equipment that holds value, money that buys bay time.
More: Independent repair shops
Service centers fall in this group too.
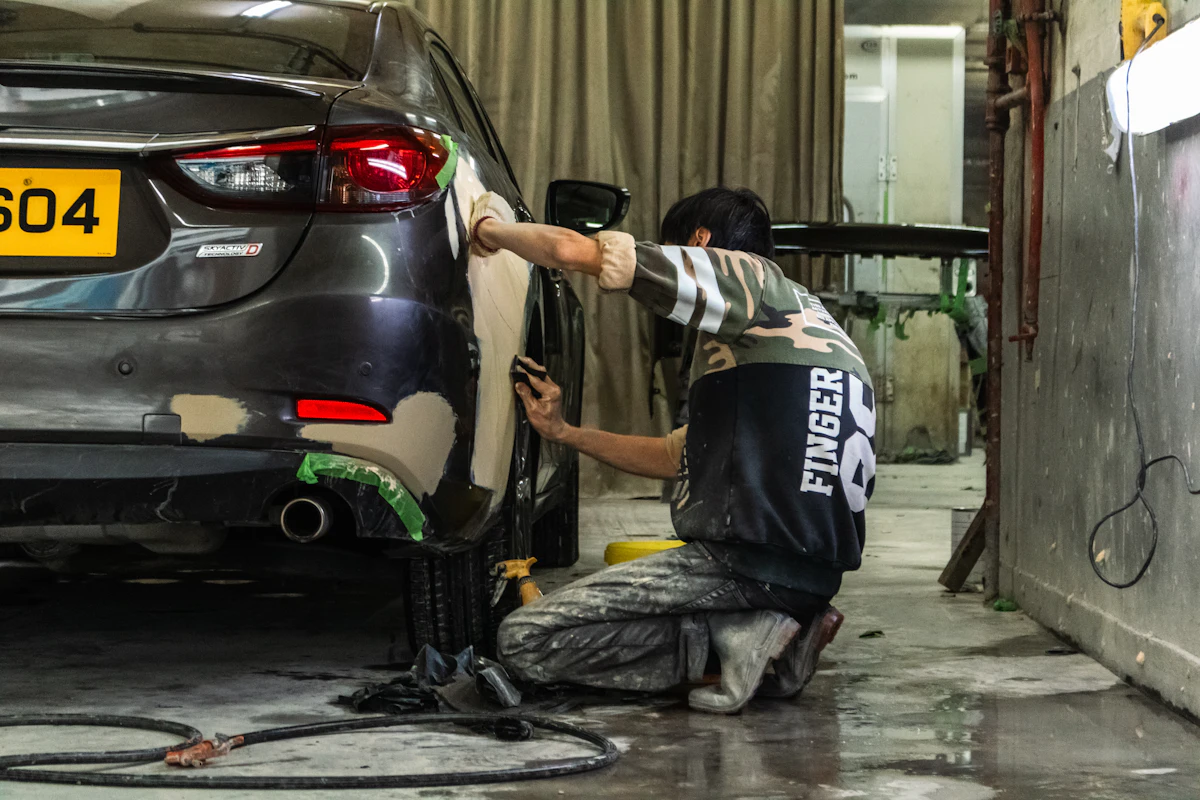
Body and collision shops
Larger tickets and slow insurance-paid receivables. Paint booths and frame equipment are real capital purchases.
More: Body and collision shops
Served by providers in our network, with the slow receivables as the caveat.
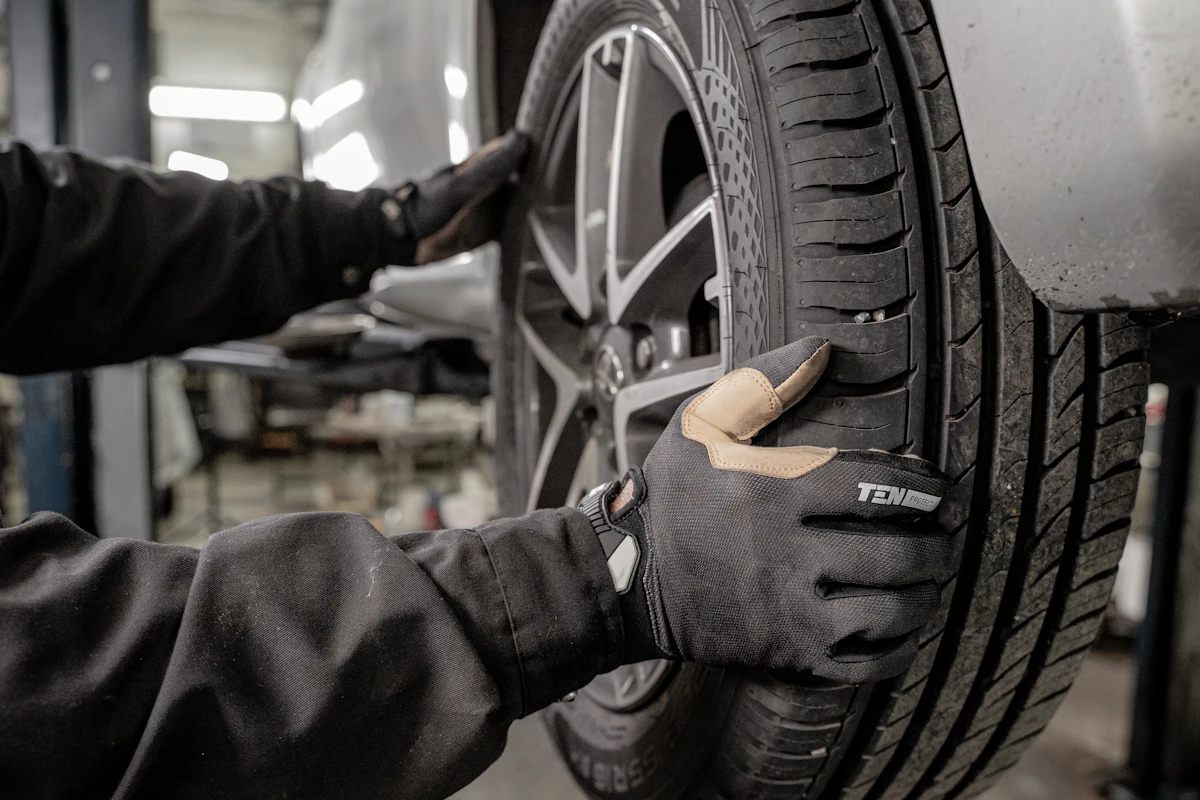
Tire shops
Inventory-led. The amount tracks the buying cycle, so a line of credit usually fits and seasonality needs explaining.
More: Tire shops
Tire machines can also be financed as equipment, where the machine secures the deal.
Diesel and specialty shops
Transmission and specialty work is equipment-led and well served; the specialist tool secures its own financing.
More: Diesel and specialty shops
The specialist tool is often the thing that wins the work.
Car washes
Served, but the need differs: tunnel and reclaim systems, and often an acquisition, which points to SBA loans, full financial statements and weeks, not days.
Mobile mechanics and newer shops
Vans and tools are financeable; time in business is the hurdle. Under the 12 months most providers want, try startup business financing or equipment financing for startups.
Auto sales: dealers and used-car lots
Not served by most providers in our network; a few decline outright. Lumpy large-ticket revenue, inventory financed elsewhere, buy-here-pay-here lending few can underwrite.
What does an auto repair business need to apply?
Some providers consider applications at these minimums. Meeting a minimum does not guarantee an offer. The application is a soft credit pull only.
12 mo
time in business
$15K
monthly revenue
525
credit considered from
3 mo
bank statements
5 min
application
Bring, on top of the statements
- A government ID
- More statements in some states: four in CA, NY, FL and GA with some providers
- A quote or invoice for any equipment you are financing
- Your repair or environmental licence if your state issues one
- A one-line answer to what the money is for
"A second lift and the parts to keep it busy" reads better than "working capital".
Capital Gurus is not a lender. We collect your application, present it to funding providers in our network, and help you compare the offers they make. Each provider sets its own rates, fees and terms, which are disclosed in that provider's agreement.
Frequently asked questions
In short
Repair shops place well with providers in our network: steady card and fleet-account deposits, equipment that holds its value, and spending that pays for itself. Working capital financing is the lead product for this industry, with equipment financing beside it. Providers consider $10K–$10M, depending on the funding provider. Auto dealers and used-car sales are excluded by most providers.
Can an auto repair shop get working capital financing?
Usually, yes. Repair shops are one of the more straightforward files in our network, because the revenue arrives as card settlements and fleet-account payments straight into the business account, which is what providers read. Some providers consider credit from 525 with 12 months in business and $15,000 in monthly revenue.
Can I finance a lift, an alignment rack or a scan tool?
Yes, and this is the clearest equipment case in the industry. The machine secures the deal, so the cash in your account stays there. Providers in our network consider up to $500K on the application alone and up to $5M with full documentation, depending on the funding provider. New and used both get financed; used normally means a shorter schedule.
Do providers fund car dealers or used-car lots?
Most do not. Auto sales — franchised dealers, used-car lots, buy-here-pay-here operations — is excluded by most providers in our network, and a few decline it outright. This is the one honest warning on this page: if your revenue comes from selling vehicles rather than from servicing them, you are a different file and this is not the right queue.
What do providers look at on a repair shop's file?
Deposit consistency first: revenue in every month of statements, not one strong month after a weak one. Then negative balance days, complete statements with no missing pages, financing already in repayment, and your credit profile. Shops whose revenue is largely cash are harder to size, because a provider can only underwrite what reaches the bank.
Can I finance buying a car wash?
An acquisition is usually an SBA conversation rather than a working capital one, because the schedules are long and real estate is often part of the deal. Capital Gurus is not an SBA lender; SBA loans are made by SBA-participating lenders. Expect weeks rather than days, full financial statements and tax returns, and a decision made by the lender under SBA rules.
I need to pay for my own car repair. Is this that?
No. This page is about financing for the business that does the repair — the shop, its equipment, its parts and its payroll. Consumer financing for your own repair bill is a different product from a different kind of provider, and Capital Gurus does not arrange it. Ask the shop whether it offers a customer payment plan.
Still have a question?
talk to a funding advisorDecisions from some providers the same day, depending on the provider.
Subject to provider approval and document turnaround.
about 5 minutes, soft credit pull only · Talk to a funding advisor