
Retail Business Loans and Financing: Inventory, Seasonal Stock and Store Growth
Working capital for inventory, payroll and seasonal gaps. A build-out or second store takes another structure.
Soft credit pull only, no obligation
- Same-day decisions
- from some providers
- Subject to provider approval and document turnaround.
- 700+
- industries served
- Reviews
- Order paid
- Stock arrives
- Season pays back
Months later
Bridged by working capital financing for retail stores
Rates, factor rates, fees and terms are set by the funding provider that makes your offer and are disclosed in that provider's agreement. Figures on this page are illustrative ranges from providers in our network, not offers.
The structure that fits first
- Lead productWorking capital
The usual umbrella for a store's file: inventory, payroll, a slow month
Providers read card settlements and deposits before the balance sheet.
working capital financing - Business line of credit
Standby capital for a repeating buying cycle: draw, repay, draw again
For a buying cycle that comes back every year, not a one-off order.
a business line of credit - Business term loan
One inventory order or one build-out, on a fixed schedule you can budget
When one inventory order has a known cost and a known selling window.
a business term loan - Merchant cash advance
Card-heavy takings, and credit that is weaker than the deposits
A purchase of future receivables, not a loan, priced with a factor rate.
a merchant cash advance
Decisions from some providers the same day, depending on the provider.Subject to provider approval and document turnaround.
The numbers before you apply
Typical amount
$10K–$10M
Across the products in our network
Working capital
Up to $10M
For strong files — inventory, payroll, a slow month
Speed
As fast as 6 hours
Same-day decisions from some providers; funding as fast as 6 hours, subject to provider approval and document turnaround
Amounts considered by providers in our network, depending on the funding provider. Not an offer. Cost is stated on each product page.
What do retail stores use financing for?
Six requests cover most of what store owners ask us about.
- Most common
Seasonal inventory
The order has to be placed and paid for long before the season pays you back.
More: Seasonal inventory
This is the most common reason a store applies, and the one that suits revenue-tied funding best, because the stock produces the sales the remittance comes out of.
Supplier terms and bulk pricing
A supplier who wants payment up front, or a bulk price break, is a cash-flow problem.
More: Supplier terms and bulk pricing
It has a measurable return attached: work out the discount first, then the cost of the funding, then compare the two.
The slow stretch between seasons
Rent, payroll, utilities and insurance carry on when the floor is quiet.
More: The slow stretch between seasons
A predictable trough is a gap rather than a structural problem, and standby capital arranged before it does more than a lump sum arranged during it.
Build-out, refit and fixtures
Shelving, lighting, flooring, a counter, a point-of-sale system, a sign, a window: spend that lasts for years.
More: Build-out, refit and fixtures
It should not be paid out of a few weeks of takings, so a term structure usually fits this better than an advance.
A second location
Deposit, build-out and opening stock all land at once, and the file is read on the trading history of the store you already run.
More: A second location
A store that has not opened has no statements to read, so most providers will not consider it until it has been trading for a while.
Something you did not choose
A tax bill, a common-area charge, a refrigeration failure, a repair that closes part of the floor until it is done.
More: Something you did not choose
A line of credit opened beforehand covers them, because draws are quick once the line is in place.
What do providers look for in a retail file?
Card settlements and deposits
Volume matters; consistency matters more.
More: Card settlements and deposits
A provider reads every month in the statements, not the strongest one.
Seasonality cuts both ways
A strong quarter lifts the amount a provider will consider.
More: Seasonality cuts both ways
The thin months pull it back down, because most providers size from an average. Timing your application is therefore a real lever, and one of the few you control.
Stock is rarely collateral
Providers discount stock heavily: it is hard to value.
More: Stock is rarely collateral
It turns over and is slow to sell after a default. Some providers file a general lien on business assets instead, and a personal guarantee is commonly required.
Negative days and overdrafts
Negative balance days often get a file reduced or declined.
More: Negative days and overdrafts
A provider reads every month in the statements, so they count wherever they fall.
Existing positions
Funding that is already remitting reduces what a provider will add, and some providers decline stacked files outright.
Your lease
Remaining term, percentage rent and landlord consent to a build-out come up on larger or premises-linked requests.
What you sell
Some providers restrict particular retail categories; where one does, another may accept the same file.
Complete statements
Partial months, missing pages and screenshots stall a file longer than any other document problem.
Worked example
A store wants stock on the floor before its peak quarter and asks for an advance against card settlements. The arithmetic on an advance is deliberately simple: the funded amount multiplied by the factor rate gives the payback amount, and the difference between the two is the cost.
Funded amount
$75,000
Factor rate
Set by the provider
Payback amount
$93,750
- Cost of the advance
- $18,750
- Remittance
- An agreed percentage of card settlements
- Estimated payback period
- 3 to 18 months
Illustrative example, not an offer. Factor rates, fees and remittance schedules are set by the funding provider that makes your offer and are disclosed in that provider's agreement. An advance is not a loan and carries no interest; any annualized figure is shown for comparison only.
Which kind of store you run
Specialty retail and boutiques
Small tickets, steady card takings, little to pledge. An advance or a small line are the usual answers.
Multi-location retail
Statements from every account, consolidated figures, and a request sized on the group rather than on one store.
Franchise retail
The franchise agreement, the franchisor's approval and any mandated refresh programme all shape the file and the timing.
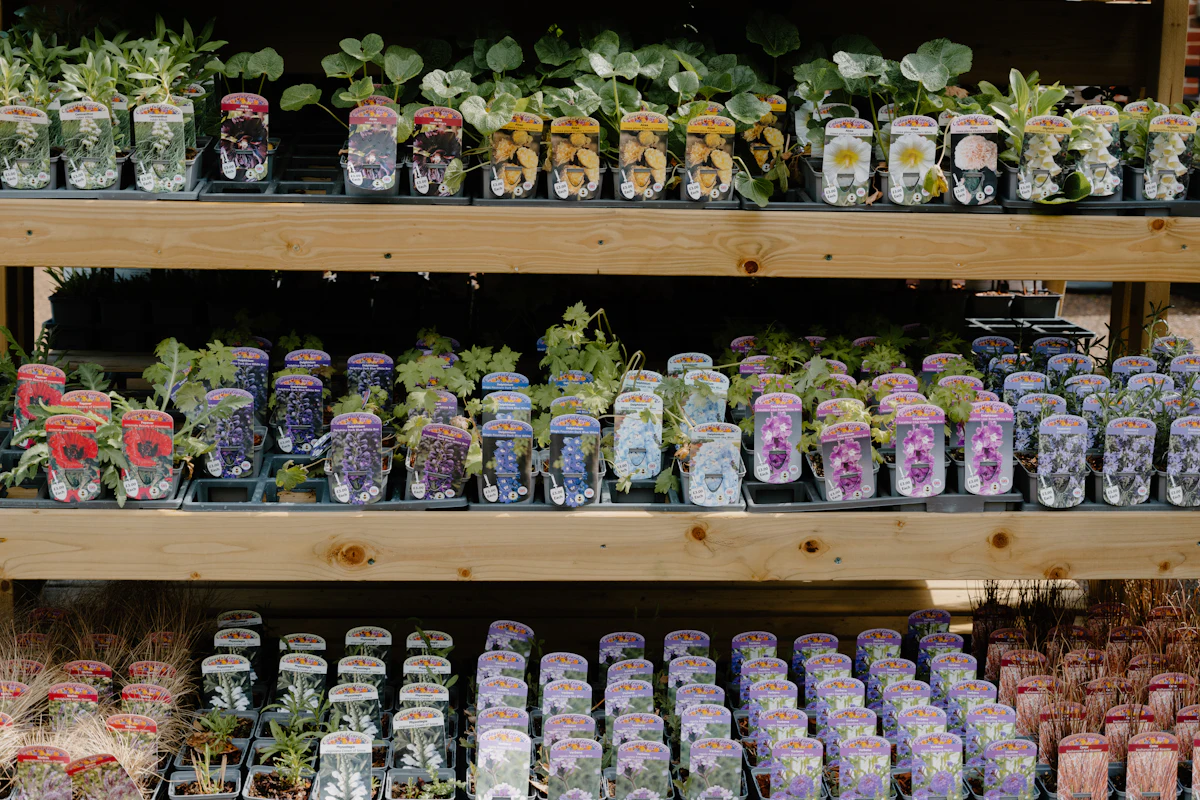
Seasonal-only retail
Garden centres, holiday and festival stores, beach and ski shops. Expect the quiet months to be averaged in, and apply at the top of the cycle where you can.
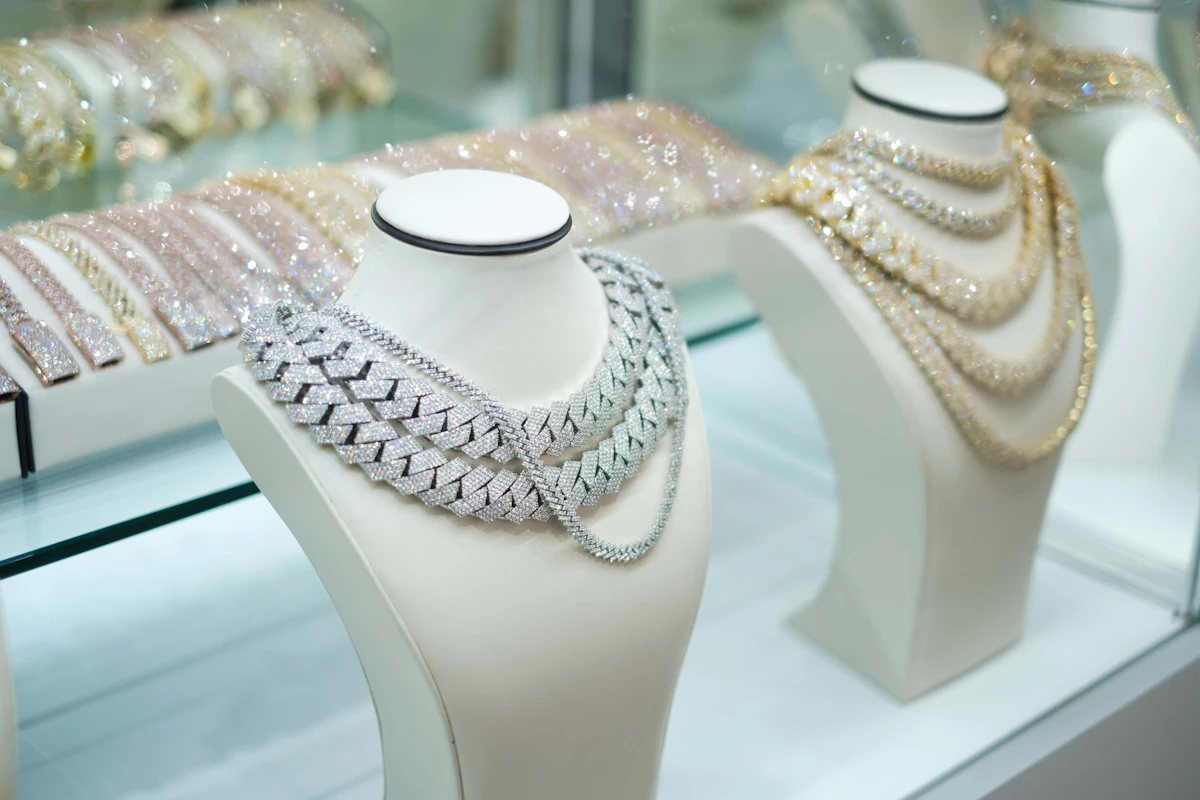
High-ticket retail
Furniture, jewellery, appliances. Fewer and larger sales make deposits lumpier, which reads as less consistent even in a good year, so be ready to explain the pattern.
What does a retail store need to apply?
Some providers consider applications at these minimums. Meeting a minimum does not guarantee an offer. The application is a soft credit pull only.
12 mo
time in business
$15K
monthly revenue
525
credit considered from
3 mo
bank statements
5 min
application
Bring, on top of the statements
- A government ID
- More statements in some states: four in CA, NY, FL and GA with some providers
- Processor statements. Where the request is tied to card settlements, the processor's own statements shorten the review.
- The number and the reason. How much you need, what it is for and when you need it. Providers ask, and some restrict certain uses.
- Existing positions. List anything already remitting. It will be found in the statements, and finding it late costs days.
Capital Gurus is not a lender. We collect your application, present it to funding providers in our network, and help you compare the offers they make. Each provider sets its own rates, fees and terms, which are disclosed in that provider's agreement.
Frequently asked questions
In short
Most retail stores fund inventory, payroll and seasonal gaps with working capital — a term loan, a line of credit or a revenue-based advance against card settlements. Providers in our network consider $10K–$10M across products, with same-day decisions from some providers. A build-out or a second location usually needs a different structure.
What kind of financing do retail stores usually get?
Working capital, in one of three shapes: a revenue-based advance collected from card settlements, a line of credit you draw against each buying cycle, or a term loan for one inventory order. Which one your file reaches depends on your deposits and your credit profile more than on the fact that you run a store. Each structure has its own cost, disclosed in the provider's agreement.
Can I use my inventory as collateral?
Rarely on its own. Providers in our network discount stock heavily, because it turns over, it is hard to value and selling it after a default is slow. Some providers file a general lien on business assets instead, and a personal guarantee is commonly required. What applies to you is set out in the agreement you sign, so read it before you sign it.
How do providers handle a seasonal store?
They read every month of statements and size from the average, which cuts both ways. A strong quarter lifts the amount a provider will consider; the thin months pull it back down. The same store reads stronger at the top of its season than at the bottom of one, so arrange funding before the buying season rather than during it.
How fast can a store be funded?
same-day decisions are available from some providers, and funding as fast as 6 hours in some cases, subject to provider approval and document turnaround. Speed follows the structure: an advance reviewed on bank statements moves quickest, while a line or a term loan that needs tax returns takes longer. Complete statements are the one part of the timeline you control.
Can a store with weak credit get financing?
Often, yes, but the structure changes rather than the answer. Some providers consider credit from 525 with 12 months in business and $15,000 in monthly revenue. At that profile the realistic offer is usually an advance against card settlements rather than a term loan, with a shorter payback and a smaller first amount.
Can I get funding for a second location or a store that has not opened?
A second location is normally funded on the trading history of the first, so providers read the existing store's deposits. A store that has not opened has no receivables to advance against and no statements to read, so most providers in our network will not consider it until it has been trading and banking for a while. Meeting a minimum does not guarantee an offer.
Still have a question?
talk to a funding advisorDecisions from some providers the same day, depending on the provider.
Subject to provider approval and document turnaround.
about 5 minutes, soft credit pull only · Talk to a funding advisor