
Landscaping and Lawn Care Business Loans and Financing: Mowers, Trucks, Spring Mobilisation and the Off-Season
Working capital for the off-season months, and equipment financing for mowers, trucks and trailers.
Soft credit pull only, no obligation
- Same-day decisions
- from some providers
- Subject to provider approval and document turnaround.
- 700+
- industries served
- Reviews
- Spring mobilisation
- First invoices
- Cash lands
About sixty days
Bridged by working capital financing for landscaping and lawn care companies
Rates, factor rates, fees and terms are set by the funding provider that makes your offer and are disclosed in that provider's agreement. Figures on this page are illustrative ranges from providers in our network, not offers.
The structure that fits first
- Lead productWorking capital
Sized from the deposits in your statements, not a finished job
For the mulch, seed, fuel and first six weeks of crew payroll that land before a single spring invoice clears.
working capital financing - Equipment financing
The machine secures the deal, so the season's cash stays put
For mowers, trucks, trailers and skid steers, the deal is tied to the machine, not to your season's cash.
equipment financing - Business line of credit
Standby capital, drawn and redrawn as you pay it down
A business line of credit is the better shape when the same gap reopens every year, through the winter trough.
business line of credit - Business term loan
A known amount with a known end date: a yard, a shop, a route purchase
A business term loan suits a yard, a shop, a route purchase or a fixed project with a known end date.
business term loan
Decisions from some providers the same day, depending on the provider.Subject to provider approval and document turnaround.
The numbers before you apply
Typical amount
$10K–$10M
Across the products in our network
Equipment amounts
Up to $5M
Up to $500K on the application alone; up to $5M with full documentation
Speed
As fast as 6 hours
Same-day decisions from some providers; funding as fast as 6 hours, subject to provider approval and document turnaround
Amounts considered by providers in our network, depending on the funding provider. Not an offer. Cost is stated on each product page.
What do landscaping and lawn care businesses use financing for?
- Most common
Mobilizing crews and supplies for spring
Supplies, insurance renewals and a crew rehired before the first invoice is paid.
More: Mobilizing crews and supplies for spring
Mulch, seed, fertilizer, plant material, fuel and uniforms. This is the single most common reason a landscaper applies, and the clearest case for working capital.
Crew payroll before the first invoices clear
Route customers often pay on the day; commercial accounts run on net terms.
More: Crew payroll before the first invoices clear
Commercial grounds and property-management accounts set those terms. The crew is paid weekly either way.
Mowers, trucks and trailers
Zero-turns, a skid steer, a chipper: each financed against the machine itself.
More: Mowers, trucks and trailers
Stand-ons, a dump trailer, an aerator and trucks too. A machine that works for years should not be paid for out of one spring's receipts.
Getting through the winter trough
Shop rent, insurance, a truck payment and key crew keep running while revenue does not.
More: Getting through the winter trough
Key crew means the two or three people you cannot afford to lose. This is the gap landscapers underestimate most.
A pivot into snow and ice
Plows, spreaders, salt and a stocked yard, all bought before the first storm.
More: A pivot into snow and ice
That spend lands in a month when maintenance money has already slowed. Snow and ice contracts put deposits in the months a maintenance route does not, so the file reads as a twelve-month business.
What do providers look for in a landscaping file?
Twelve months, not your best three
Underwriting looks for a pattern that repeats, season after season.
More: Twelve months, not your best three
A northern maintenance company with four strong months, four moderate ones and four quiet ones is a normal landscaping file; the same statements with no explanation look like a business in decline. The pattern has to be visible, which is why complete months matter more here than in a retail file. Send three months of bank statements with every page, and name the season on the application.
The month you apply in changes the answer
This is the part most owners find out the hard way.
More: The month you apply in changes the answer
Working capital is sized from recent deposits, so a file submitted in February is read against your trough and a file submitted in May is read against your peak. The business has not changed; the three months on the desk have. If you can see the need coming, apply while the deposits are strong — a line of credit arranged in July is there in January, and one applied for in January is sized by January.
Deposit mix: route work versus contracts
Residential mowing is small, frequent and paid promptly, and reads as steady deposits.
More: Deposit mix: route work versus contracts
Commercial grounds contracts and HOA or property-management accounts are larger, invoiced on net terms, and sometimes concentrated in one or two customers. Providers size an offer against concentration risk, so say how your revenue splits.
Negative balance days in the trough
A handful of overdraft days in the quiet months is common and survivable.
More: Negative balance days in the trough
A pattern of them says the trough is not funded, and that moves a decision more than a weak month does.
Equipment is tied to the machine
Equipment financing is not a general loan with a mower attached.
More: Equipment is tied to the machine
The deal is secured by the mower, truck, trailer or skid steer itself, which is why the vendor quote, the hours, the serial number and the resale market for that model all move the decision. A machine with a deep second-hand market finances more easily than one with almost none, whatever your credit profile looks like. Counter-seasonal revenue helps too: snow and ice contracts put deposits in the months a maintenance route does not.
Worked example
A grounds maintenance company in a northern market is six weeks out from the spring ramp. It has won two new commercial contracts, needs a second mowing crew, and the first invoices on those contracts will not pay for roughly sixty days. One application, two structures.
Equipment financing
$85,000
Two zero-turn mowers and a dump trailer
The machines secure the deal
Working capital
$40,000
Mulch, seed, fuel and six weeks of crew payroll
Illustrative example, not an offer. Amounts, costs and schedules are set by the funding provider that makes your offer and are disclosed in that provider's agreement. Financed equipment may qualify for a depreciation deduction — consult a tax advisor.
Routes, contracts, design-build, tree care and snow
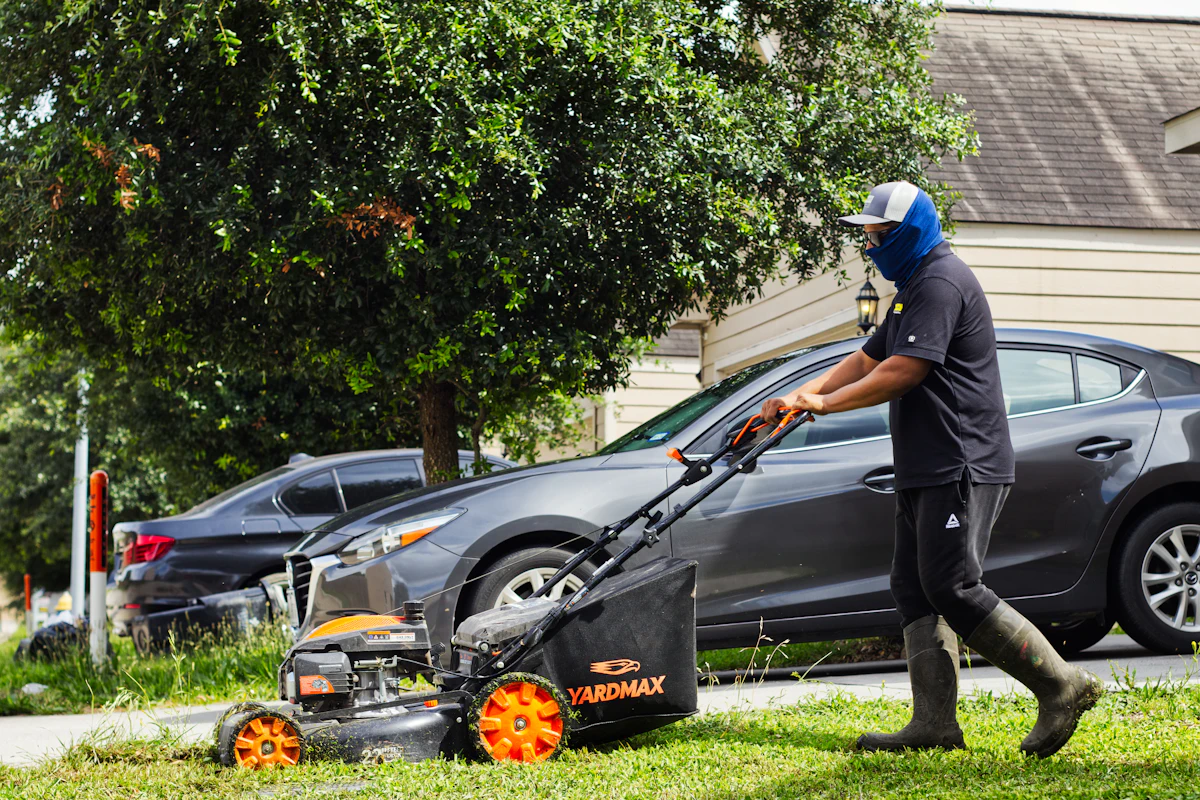
Residential maintenance routes
Small, steady, promptly paid tickets. Low revenue per customer keeps first offers modest; growth comes through renewals.
More: Residential maintenance routes
Deposits look steady and the files are easy to read; the growth path runs through renewals rather than one large amount.
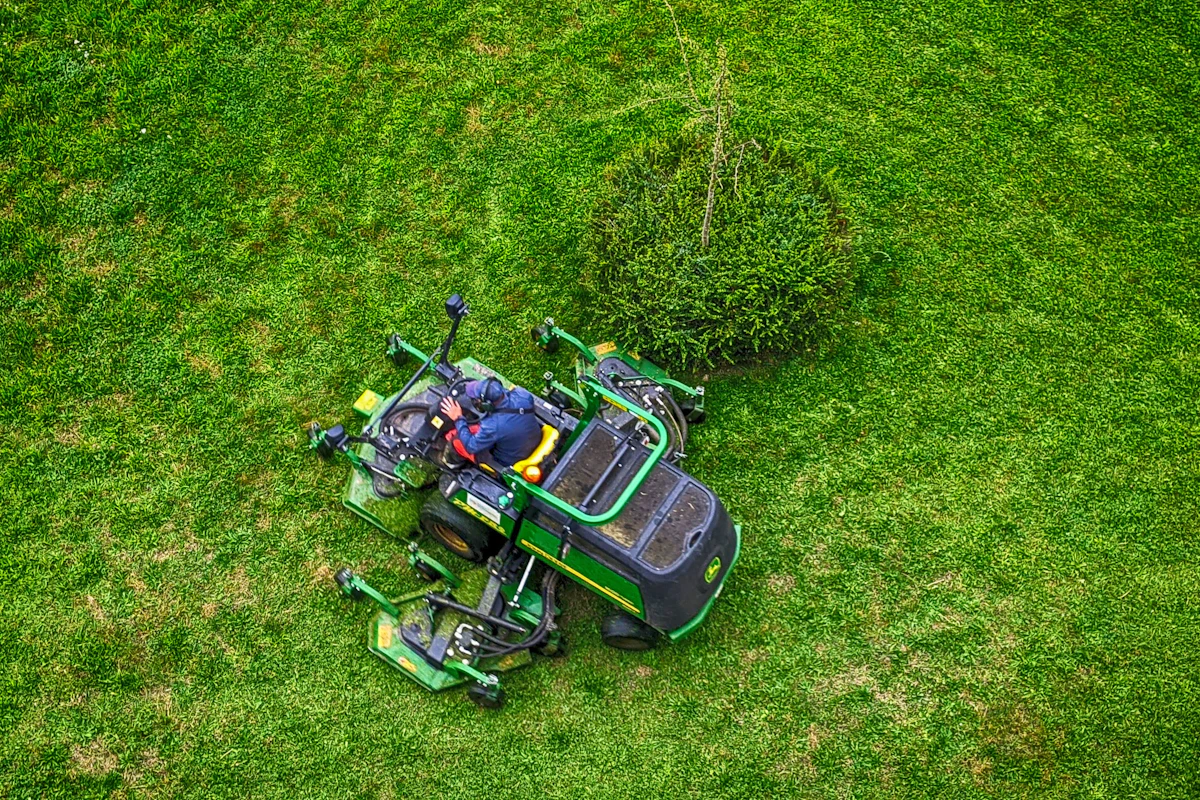
Commercial grounds and HOA contracts
Net terms, often one or two dominant accounts, and the longest payroll gap: arrange a line of credit before the season.
More: Commercial grounds and HOA contracts
These property-management contracts bring larger revenue, but real concentration risk when one or two accounts dominate. They are the files where a line of credit earns its keep.
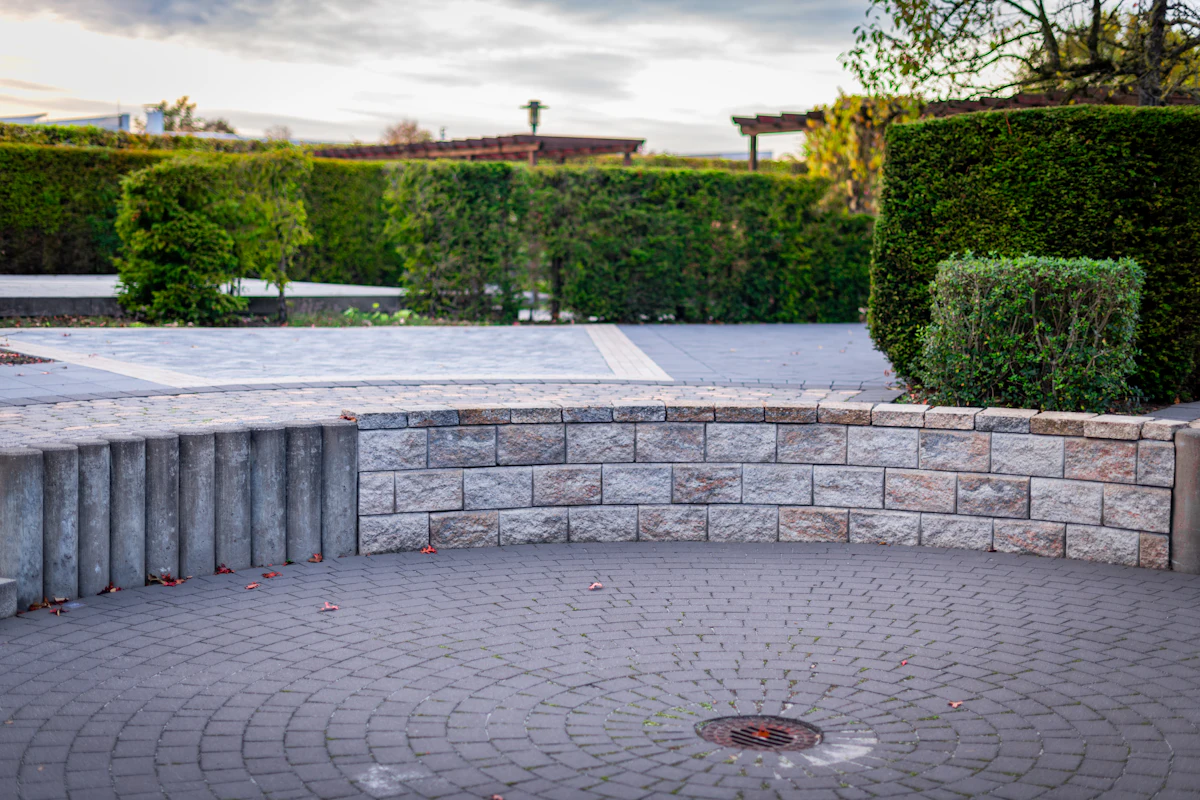
Design-build, hardscape and installation
Project-based, with materials and sub-labor bought ahead of the work. Lumpy deposits are normal; say so on the application.
More: Design-build, hardscape and installation
Materials, pavers and plant stock are often bought against a smaller customer deposit that covers less than the outlay. Saying the work is project-based keeps the pattern from being misread.
Tree care and arborist services
The most equipment-heavy corner: chippers, bucket trucks, stump grinders, cranes. Equipment financing leads.
More: Tree care and arborist services
Tickets are larger and insurance requirements heavier. The equipment financing hub carries the answers for this corner of the trade too.
Irrigation and outdoor lighting
Parts-led and sharply seasonal in cold markets: spring start-ups and fall blow-outs concentrate revenue into a few weeks, while fixed costs run all year.
Snow and ice management
The counter-season, and the single most useful fix for the curve: a landscaper who plows reads as a twelve-month business on a bank statement, which makes the file easier to read.
New and one-truck operations
Under most minimums: startup business financing or equipment financing for startups on the first mower and trailer. How to get a startup business loan sets out what is realistic.
What does a landscaping business need to apply?
Some providers consider applications at these minimums. Meeting a minimum does not guarantee an offer. The application is a soft credit pull only.
12 mo
time in business
$15K
monthly revenue
525
credit considered from
3 mo
bank statements
5 min
application
Bring, on top of the statements
- A government ID
- More statements in some states: four in CA, NY, FL and GA with some providers
- The vendor quote if the request is for a machine
- A short note on how your revenue splits between route work and contracts
- One line on where you are in the season
Providers ask what the funds are for, and a specific answer — a named mower and trailer, spring materials, payroll until two contracts pay — reads better than "working capital".
Capital Gurus is not a lender. We collect your application, present it to funding providers in our network, and help you compare the offers they make. Each provider sets its own rates, fees and terms, which are disclosed in that provider's agreement.
Frequently asked questions
In short
Landscaping and lawn care businesses earn most of their money in a few months and pay bills in all twelve. Working capital financing is the lead product for this industry through Capital Gurus' network, with equipment financing for mowers, trucks and trailers beside it. Providers in our network consider $10K–$10M, depending on the funding provider.
Can a landscaping business get financing in the off-season?
Yes, and many do, but the number is usually smaller. Providers size working capital from recent deposits, and in January the recent months are your quietest ones. The same file read in April reaches more. If you know the trough is coming, arrange the capital while the deposits are still strong, because a line is easier to open in season than during it.
How do providers read seasonal deposits?
Across a full year rather than your best quarter. What they look for is a curve that repeats: a predictable trough reads as a timing pattern, while an unexplained collapse reads as a failing business. Send three months of bank statements as complete months with all pages, and say on the application which part of the season those statements cover.
Can I finance mowers, trucks and trailers?
Yes, and the asset carries part of the decision. Equipment financing is tied to the mower, truck or trailer itself, so a weaker credit profile is less decisive than it is on a term loan. Some providers consider up to $500K on the application alone, and up to $5M with full documentation. Expect a vendor quote, a deposit, and a shorter schedule on a machine with hours on it.
Can a new lawn care business qualify?
Some providers in our network consider applications from 12 months in business with $15,000 in monthly revenue and credit from 525. Below that, the realistic routes are startup business financing or equipment financing against the first mower and trailer, at a smaller amount and on a shorter schedule than an established route would reach.
Does snow and ice work help the application?
Usually, yes. Winter contracts turn a trough into a second season, and a file with deposits in all twelve months is read as a year-round business rather than a seasonal one. Say so on the application and make sure the statements show it. Providers still read the whole year, so a first winter of snow work moves the number less than a third one.
Is landscaping a restricted industry?
Not generally. Lawn care and grounds maintenance are accepted by most providers in our network, so the obstacle is rarely the trade itself. What varies between providers is how each one treats the seasonal curve, how small a first offer is in a quiet month, and whether residential route work or commercial contracts dominate your deposits.
Still have a question?
talk to a funding advisorDecisions from some providers the same day, depending on the provider.
Subject to provider approval and document turnaround.
about 5 minutes, soft credit pull only · Talk to a funding advisor