
HVAC, Plumbing, Electrical and Roofing Business Loans and Financing: Vans, Tools, Payroll and Seasonal Gaps
Working capital for payroll and slow seasons, and equipment financing for vans, trailers and tools.
Soft credit pull only, no obligation
- Same-day decisions
- from some providers
- Subject to provider approval and document turnaround.
- 700+
- industries served
- Reviews
- Crew paid weekly
- Work signed off
- Payment released
Weeks later
Bridged by working capital financing for home services and specialty trades
Rates, factor rates, fees and terms are set by the funding provider that makes your offer and are disclosed in that provider's agreement. Figures on this page are illustrative ranges from providers in our network, not offers.
The structure that fits first
- Lead productWorking capital
Payroll, materials and a slow season; sized from your deposits
Providers in our network read the deposits in your bank statements, not only the credit score, so the busy season can pay for payroll in the quiet one.
working capital financing for home services and specialty trades - Equipment financing
Vans, trailers, lifts, machines and tool bundles; the asset is the collateral
For trucks, trailers, lifts and tool packages, equipment financing for home services and specialty trades spreads the cost over the working life of the asset.
equipment financing for home services and specialty trades - Business line of credit
A gap that keeps reappearing; drawn and redrawn as jobs close
A business line of credit for home services and specialty trades is standby capital you draw between jobs and repay as invoices clear.
a business line of credit for home services and specialty trades
Decisions from some providers the same day, depending on the provider.Subject to provider approval and document turnaround.
The numbers before you apply
Typical amount
$10K–$10M
Across the products in our network
Considered for working capital
Up to $10M
Up to $10M for strong files, depending on the funding provider
Speed
As fast as 6 hours
Same-day decisions from some providers; funding as fast as 6 hours, subject to provider approval and document turnaround
Amounts considered by providers in our network, depending on the funding provider. Not an offer. Cost is stated on each product page.
What do home services and specialty trade businesses use financing for?
Across all products, providers in our network consider $10K to $10M, depending on the funding provider. How much business financing you can get sets out what moves that number, and what working capital is gives the formula if what you need is the figure rather than the financing.
- Most common
Payroll and materials between jobs
Crews are paid weekly; customers and general contractors pay on sign-off.
More: Payroll and materials between jobs
The gap is the most common reason a trade business applies at all.
A van, a trailer or a tool package
Financed over its working life, a fitted truck or trailer earns its keep job by job.
More: A van, a trailer or a tool package
Some providers write one agreement across a bundle of vehicles and tools rather than one per item.
A seasonal peak you can see coming
Install season for HVAC, storm season for roofing, the first freeze for plumbing.
More: A seasonal peak you can see coming
The capital is needed before the revenue, every year — as is the supplier deposit on a contract you have already signed.
A second crew, or a truck that has stopped earning
Growth in the trades is hiring, and a crew costs money for a month or two before it earns any.
More: A second crew, or a truck that has stopped earning
A dead truck is the same problem in reverse: lost revenue by the day.
What do providers look for in a trade business?
Deposits through the off-season
Providers review three months of bank statements, and they want the quiet months in them as well as the peak.
More: Deposits through the off-season
A trade whose statements cover only the peak looks like a business that earns evenly, so the first slow month reads as a decline. Send complete months, all pages, no screenshots.
Deposits that arrive in lumps
You are paid when a job closes or when a general contractor releases a payment, not in a daily card settlement.
More: Deposits that arrive in lumps
Lumpy deposits are normal here and providers underwrite them. What hurts a trade file is the negative balance days in between.
A current license, in the right name
Most providers check that the required license is active in your state and held by the business, not by an owner personally.
More: A current license, in the right name
General liability and workers' compensation are checked the same way.
Which trade, and what kind of work
Some providers in our network treat plumbing, electrical and roofing as preferred segments.
More: Which trade, and what kind of work
Others are more cautious about new-home construction and residential remodeling. A file one provider restricts is routine for another, which is the argument for one application to a network.
Where you operate, and what is already remitting
Some providers ask for additional months of bank statements in certain states before they will size an offer.
More: Where you operate, and what is already remitting
Payments already leaving the account reduce what a provider will add, and some decline stacked files outright.
Worked example
A plumbing and heating contractor running two crews goes into autumn with a signed maintenance book, a van that has stopped earning, and a supplier asking for a deposit.
Equipment financing
$96,000
Two fitted-out service vans
Working capital financing
$40,000
Material deposits and payroll before the peak
Illustrative example, not an offer. Two products rather than one: the vans and tools go on equipment financing, where the equipment is the collateral and the schedule runs over the asset's working life, and the operating need goes on working capital financing, where the schedule is short because the revenue arrives within the season.
HVAC, plumbing, electrical and roofing contractors
HVAC contractors
Installs are paid before invoices clear and shoulder months still carry crews: standby capital, set up in advance.
More: HVAC contractors
HVAC runs on two peaks and two troughs a year, and the capital is always needed on the wrong side of them. Install season needs equipment on the shelf and crews on the road before a single invoice is paid. That is why the usual answer is standby capital arranged in advance rather than a lump sum arranged in a panic.
Plumbing contractors
Service calls keep deposits the steadiest in the trades; new-build and remodel work pays weeks after the crew does.
More: Plumbing contractors
Emergency work does not wait for a good quarter, and steady deposits are the strongest thing a file can show. New-construction and remodel work follows the builder's schedule instead.
Electrical contractors
Residential service pays fast, like plumbing. Commercial work runs like construction: retainage and pay applications.
More: Electrical contractors
Electrical work pulls in two directions. Residential service and panel work means small tickets and steady deposits; commercial and industrial work means large contracts and a general contractor who pays when the pay application clears.
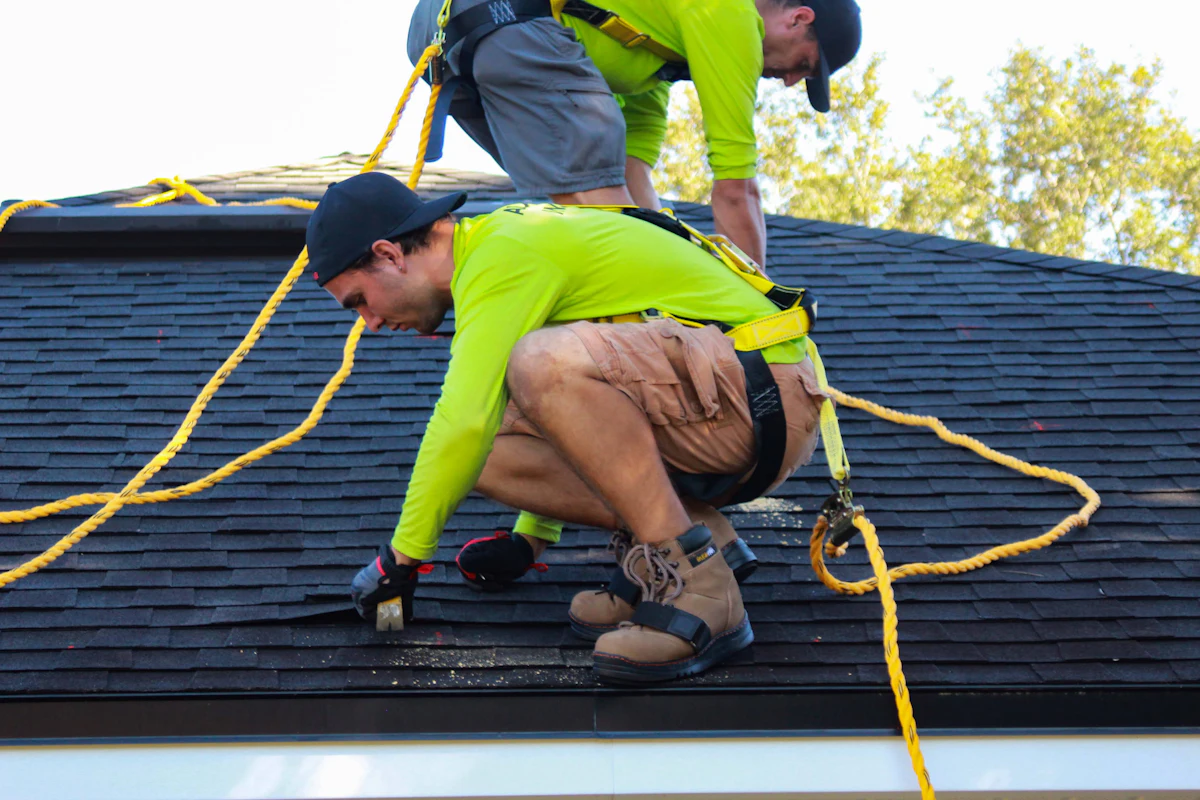
Roofing contractors
Large material deposits are due before work starts, and storm-season jobs are paid by insurance weeks later.
More: Roofing contractors
Roofing is the most front-loaded trade on this page: in storm season the volume arrives all at once. A roofer who cannot fund deposits in a storm month does not lose margin, they lose the jobs.
What does a trade business need to apply?
Some providers consider applications at these minimums. Meeting a minimum does not guarantee an offer. The application is a soft credit pull only.
12 mo
time in business
$15K
monthly revenue
525
credit considered from
3 mo
bank statements
5 min
application
Bring, on top of the statements
- A government ID
- More statements in some states: four in CA, NY, FL and GA with some providers
- Current trade licence and the insurance the work requires, in the name of the applying entity
- Equipment requests also need the vendor quote
Capital Gurus is not a lender. We collect your application, present it to funding providers in our network, and help you compare the offers they make. Each provider sets its own rates, fees and terms, which are disclosed in that provider's agreement.
Frequently asked questions
In short
Home services and specialty trade businesses — HVAC, plumbing, electrical, roofing — fund payroll, materials and seasonal gaps with working capital financing, and buy vans, trailers and tools with equipment financing. Providers in our network consider $10K–$10M across all products, with same-day decisions from some providers.
Can an HVAC or plumbing business get financing in its first year?
Sometimes, but the gate is real. Some providers in our network consider applications from 12 months in business with $15,000 in monthly revenue and credit from 525. Below that, the realistic routes are a smaller amount from a provider that works with newer businesses, or equipment financing where the van or the machine itself carries the risk.
How does a seasonal trade qualify when the off-season deposits are thin?
By letting the quiet months be visible instead of hiding them. Providers read three months of bank statements, so send complete months and say on the application which part of the year you are in. A trade with a predictable trough is a timing question, not a credit question, and arranging standby capital before the trough beats asking for a lump sum during it.
Can I finance a service van and the tools that go in it together?
Often, yes. Providers in our network finance work trucks, trailers, lifts, machines and tool packages, and some will write one agreement across a bundle rather than one per item. Equipment financing is secured by the equipment itself, which is why its credit requirements are often easier than unsecured products. Terms and fees are set by the provider and disclosed in the agreement.
Do I need my contractor licence to apply?
Expect it to be checked. Most providers verify that the licence the work requires is current, valid in the state where you work and held by the entity that is applying, along with general liability and workers' compensation where you carry crew. An expired licence, or one held by a different entity than the applicant, stalls more trade files than credit does.
What can a roofing company do when storm season outruns its cash?
The need is material deposits and crew before the money lands, which is a short, revenue-generating gap. Working capital financing fits it, and some providers in our network offer same-day decisions, subject to provider approval and document turnaround. Acceptance for roofing varies by provider: some treat the trade as a core segment, others price it more cautiously. One application reaches more than one set of guidelines.
Will applying affect my credit score?
Checking your options through Capital Gurus uses a soft credit pull only, which does not change your score. Whether on-time payments are reported to the business credit bureaus depends on the provider, so ask which bureaus it reports to before you sign.
Still have a question?
talk to a funding advisorDecisions from some providers the same day, depending on the provider.
Subject to provider approval and document turnaround.
about 5 minutes, soft credit pull only · Talk to a funding advisor