
Medical Practice Loans and Financing: Equipment, Build-Outs, Acquisition and Working Capital
Term loans and lines of credit for equipment, build-outs, buy-ins and payroll while claims clear.
Soft credit pull only, no obligation
- Same-day decisions
- from some providers
- Subject to provider approval and document turnaround.
- 700+
- industries served
- Reviews
- Work done
- Claim filed
- Money arrives
Weeks later
Rates, factor rates, fees and terms are set by the funding provider that makes your offer and are disclosed in that provider's agreement. Figures on this page are illustrative ranges from providers in our network, not offers.
The structure that fits first
- Lead productBusiness term loan
A known amount for a known project: build-out, acquisition, a second site
Term loans for medical practices lead here: $10K–$10M; some offer terms up to 10 years, depending on the funding provider.
business term loans for medical practices - Business line of credit
Standby capital for reimbursement gaps you can predict but not date
For the weeks between reimbursement cycles: draw when the claim is filed, pay it down when the remittance lands.
a line of credit for medical practices - Equipment financing
The asset secures the deal, so the machine does much of the work
Where the machine secures its own deal, and the vendor quote and the resale market for that model move the decision.
equipment financing for medical practices
Decisions from some providers the same day, depending on the provider.Subject to provider approval and document turnaround.
The numbers before you apply
Typical amount
$10K–$10M
Across the products in our network
Equipment amounts
Up to $5M
Up to $500K on the application alone; up to $5M with full documentation
Speed
As fast as 6 hours
Same-day decisions from some providers; funding as fast as 6 hours, subject to provider approval and document turnaround
Amounts considered by providers in our network, depending on the funding provider. Not an offer. Cost is stated on each product page.
What do medical and healthcare practices use financing for?
Six requests account for most of what practices ask about.
- Most common
Equipment and technology
Imaging, lasers, chairs, sterilisers, monitoring, a new practice management system.
More: Equipment and technology
This is the single most common request, and the one with the clearest structure: some providers consider up to $500K on the application alone, and up to $5M with full documentation, depending on the funding provider. Equipment Financing for Medical Practices goes through what a vendor quote needs to show.
A build-out or a second location
Leasehold improvements, plumbing and electrical for treatment rooms, signage.
More: A build-out or a second location
Also the first months of rent on a site that is not yet seeing patients. A term loan fits because the amount and the end date are both known before you start.
Practice acquisition or a partner buy-in
Buying a retiring physician's book, buying into a partnership, or buying out a partner.
More: Practice acquisition or a partner buy-in
These are full-documentation files, and they take longer than any other request on this list.
Payroll and payables between reimbursement cycles
The work is done, the claim is filed, and the money arrives weeks later. Clinical and front-desk salaries do not wait.
More: Payroll and payables between reimbursement cycles
A line of credit is the better instrument here, because you draw for the gap and pay it down when the remittance lands.
Hiring and credentialing a new physician or nurse practitioner
Every new provider costs money before they bill anything: recruitment and credentialing with each payer.
More: Hiring and credentialing a new physician or nurse practitioner
Then a salary through the ramp-up, before the first claims are paid.
Consolidating or refinancing existing obligations
Several short schedules running at once can outrun what the practice actually collects between remittances.
More: Consolidating or refinancing existing obligations
Refinancing Business Debt With a Term Loan sets out when replacing them with one longer schedule helps and when it only moves the problem.
What do providers look for in a medical practice?
Acceptance still varies: a file one provider restricts is routine for another, which is the point of applying once to a network.
Collections, read against the payer cycle
A practice is paid after the service, on a gap set by the payer, not by the practice.
More: Collections, read against the payer cycle
Providers know this. What they read for is consistency: deposits in every month of statements, few negative balance days, and a payer mix that does not depend on one contract. A practice with a heavy private-pay or cash-pay share looks different again, because the deposits track the appointments more closely.
The licence and the entity
Professional licensing is verifiable, and providers verify it.
More: The licence and the entity
Expect questions about the licensed owner, the entity that holds the licence and the entity that holds the bank account when those are not the same.
The equipment itself, on an equipment deal
Equipment financing is tied to the equipment, not only to the practice.
More: The equipment itself, on an equipment deal
The vendor quote, the serial number, the installation cost and the resale market for that model all move the decision. A machine with a deep second-hand market is easier to finance than a machine with almost none, whatever the practice's credit profile looks like.
Acquisitions, as their own exercise
A practice acquisition is underwritten on the target as much as on you.
More: Acquisitions, as their own exercise
Providers want the seller's financials, a valuation, the purchase agreement and your own returns. Some files fit a term loan; others fit an SBA path, which is measured in weeks.
The upside
This is the part worth saying plainly.
More: The upside
A practice with strong, documented collections reaches schedules and amounts that most verticals never see — some providers consider terms up to 10 years on files like these, depending on the funding provider, where a comparable request from a card-heavy retail business would be offered months instead. Strong collections are the asset here, and documenting them well does more for the file than anything else you can do before applying.
Worked example
A three-physician primary care group opening a second location, with a plan split across three structures rather than one.
Business term loan
$250,000
Build-out and rent during the ramp-up
Equipment financing
$150,000
Imaging and exam-room equipment at the new site
Business line of credit
$100,000
Payroll while the first claims from the new site clear
Left undrawn until needed
Illustrative example, not an offer. Amounts, rates, fees and schedules are set by the funding provider that makes each offer and are disclosed in that provider's agreement.
Sub-segments of healthcare
Physician practices and multi-specialty clinics
Insurance-led collections and costly but standard equipment: term loans and lines of credit lead, equipment behind them.
Dental practices and dental groups
Chairs, imaging, build-outs and frequent practice sales make it equipment-led. Dental has its own page.
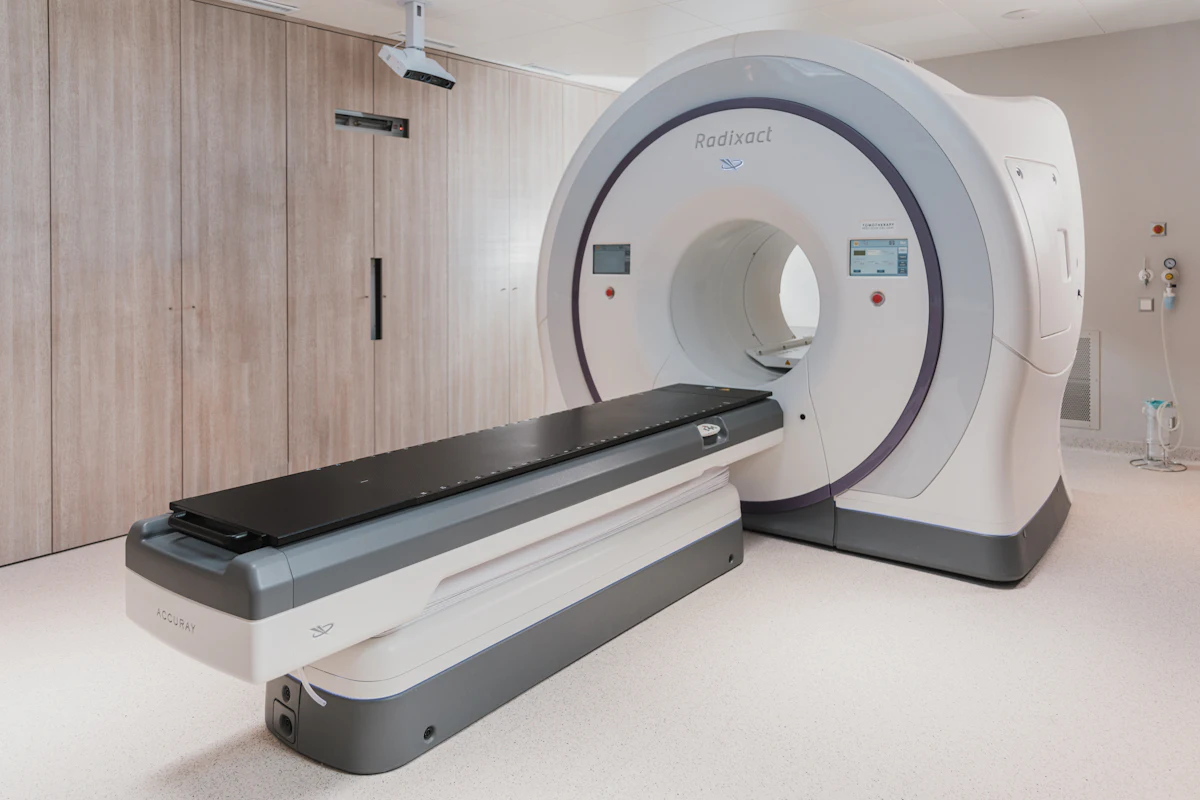
Urgent care, imaging and surgical centers
Larger tickets, heavier equipment, real estate: the files most likely to need full documents and reach an SBA conversation.
Home health, behavioral health and allied services
Payroll-heavy and often paid by a few payers; when one is most of the revenue, providers size the offer against it.
What does a medical practice need to apply?
Some providers consider applications at these minimums. Meeting a minimum does not guarantee an offer. The application is a soft credit pull only.
12 mo
time in business
$15K
monthly revenue
525
credit considered from
3 mo
bank statements
5 min
application
Bring, on top of the statements
- A government ID
- More statements in some states: four in CA, NY, FL and GA with some providers
- The licence and entity documents. Professional licence, entity registration, EIN, and the ownership split if there is more than one owner.
- The quote, for equipment. Vendor, model, serial number where it exists, delivery and installation cost.
- Tax returns and financial statements, for anything large. Acquisitions, real estate and the top of any range are full-documentation files. Business loan requirements lists what that means in practice.
- A number and a purpose. Providers ask what the money is for and some restrict certain uses, so state it on the application.
Capital Gurus is not a lender. We collect your application, present it to funding providers in our network, and help you compare the offers they make. Each provider sets its own rates, fees and terms, which are disclosed in that provider's agreement.
Frequently asked questions
In short
Medical and healthcare practices reach financing that many industries do not. The lead products are a business term loan and a business line of credit, with equipment financing and revenue-based financing behind them. Practices use them for equipment, a build-out, a partner buy-in, an acquisition, and payroll while insurance reimbursements clear. Providers in our network consider $10K to $10M.
How much financing can a medical practice get?
Collections set the number first, then the structure and your documents. Across all products, providers in our network consider $10K to $10M, depending on the funding provider. Equipment is sized against the machine: some providers consider up to $500K on the application alone and up to $5M with full documentation. Meeting a minimum does not guarantee an offer, and the top of any range belongs to full-documentation files.
Can a practice get financing while insurance reimbursements are still outstanding?
Yes, and it is one of the most common reasons practices apply. Providers read bank statements knowing that deposits arrive on payer timetables rather than at the point of service. What they look for is that the deposits do arrive, month after month. A line of credit suits that pattern better than a lump sum, because you draw only for the weeks the gap is open.
Can financing cover a practice acquisition or a partner buy-in?
It can, and it is treated as a separate exercise from working capital. Expect to produce the seller's financials, a valuation, the purchase agreement and your own tax returns. Some files fit a term loan from providers in our network; others fit an SBA loan, which takes weeks rather than days. Capital Gurus is not an SBA lender; SBA loans are made by SBA-participating lenders.
What do providers ask a medical practice for?
At minimum three months of bank statements plus a government ID. Beyond that, expect to show your professional licence, the entity documents and, for anything large, tax returns and financial statements. Equipment requests need the vendor quote. Acquisition requests need the target's numbers. Complete months and all pages matter more than any single document.
Does the practice have to pledge the equipment?
On an equipment deal, yes: the financing is tied to the equipment itself, which is why the asset's value and resale market carry so much weight. On a term loan or a line, a specific asset is not usually pledged, although a provider may file a general lien on business assets. A personal guarantee is commonly required, so read the agreement before you sign.
Can a new practice qualify?
Some providers in our network consider applications from 12 months in business with $15,000 in monthly revenue and credit from 525. A practice under a year old is usually looking at equipment financing against the machine, a smaller first amount, or the startup path rather than a long term loan.
Still have a question?
talk to a funding advisorDecisions from some providers the same day, depending on the provider.
Subject to provider approval and document turnaround.
about 5 minutes, soft credit pull only · Talk to a funding advisor