
Manufacturing Equipment Financing: Machine Tools, Production Lines, Rigging and Used Machinery
The machine carries part of the decision. The provider pays the vendor and collects on a schedule.
Soft credit pull only, no obligation
Rates, factor rates, fees and terms are set by the funding provider that makes your offer and are disclosed in that provider's agreement. Figures on this page are illustrative ranges from providers in our network, not offers.
- Same-day decisions
- from some providers
- Subject to provider approval and document turnaround.
- 700+
- industries served
- Reviews
This page answers one product for one industry: equipment financing for a manufacturer. The wider ladder a shop uses sits on financing for manufacturers; the product across every industry sits on equipment financing.
How the deal works when the asset is a machine tool
You pick the machine first, and the application is about that specific asset.
Send the quote
The vendor quote, with the model and serial number of the machine on it.
A provider decides
Against that quote and your file. The machine carries part of the decision.
The vendor is paid
Or the dealer or auction house, not your account. The provider records a lien on the machine.
You pay on schedule
Monthly, measured in years rather than months, set in the financing agreement.
The size of the deal
Small tickets are often reviewed on the application alone, up to $500K with some providers. Larger ones need full documentation, up to $5M, depending on the funding provider. Longer schedules and larger amounts need stronger credit and more paperwork.
Collateral: the machine. A personal guarantee is common: read that clause.
Loan or lease
Providers write the deal as an equipment loan or a lease. The agreement says which, who holds title at the end, what any purchase option costs, and the cost: an interest rate or a fixed cost of funds, plus any documentation, lien, inspection or appraisal fees.
What manufacturers finance
Common models with an active resale market finance most easily, because a provider must be able to sell the machine.
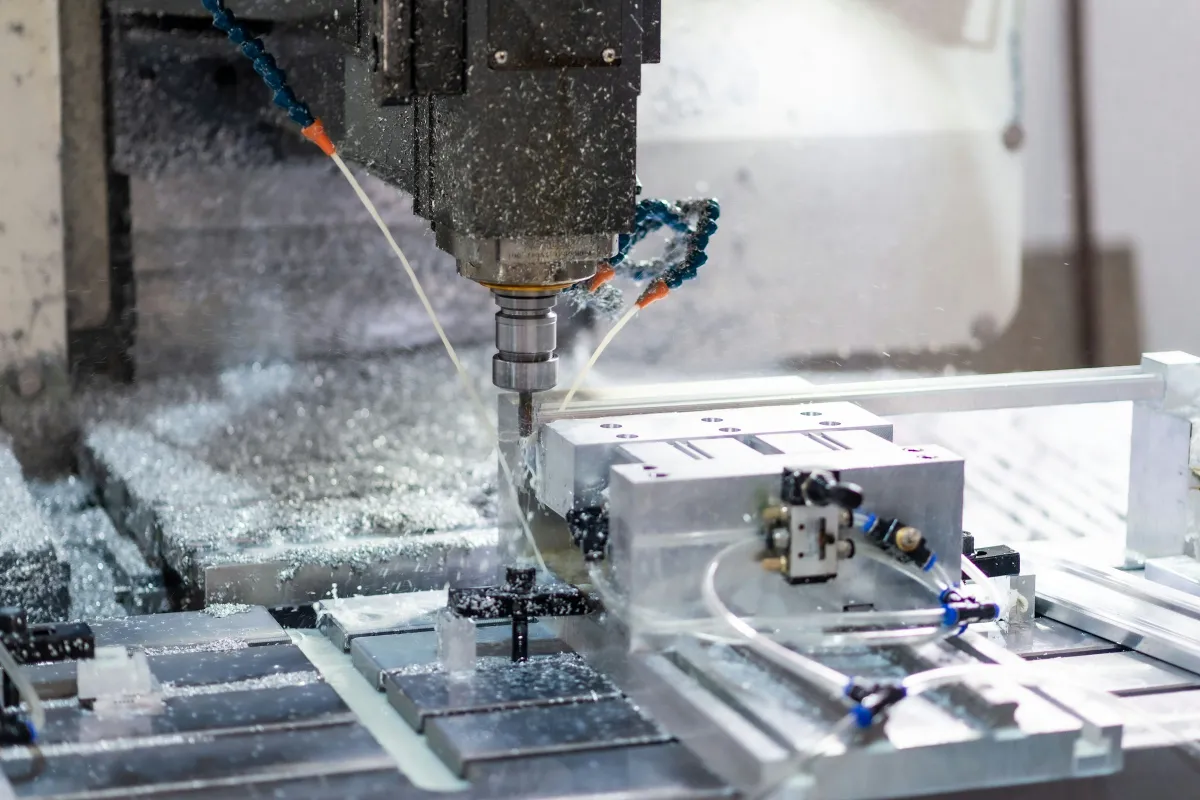
Machine tools
Machining centers, CNC lathes, press brakes, fiber lasers, waterjets, grinders, EDM.
Tooling and dies: easiest on the same deal as the machine.
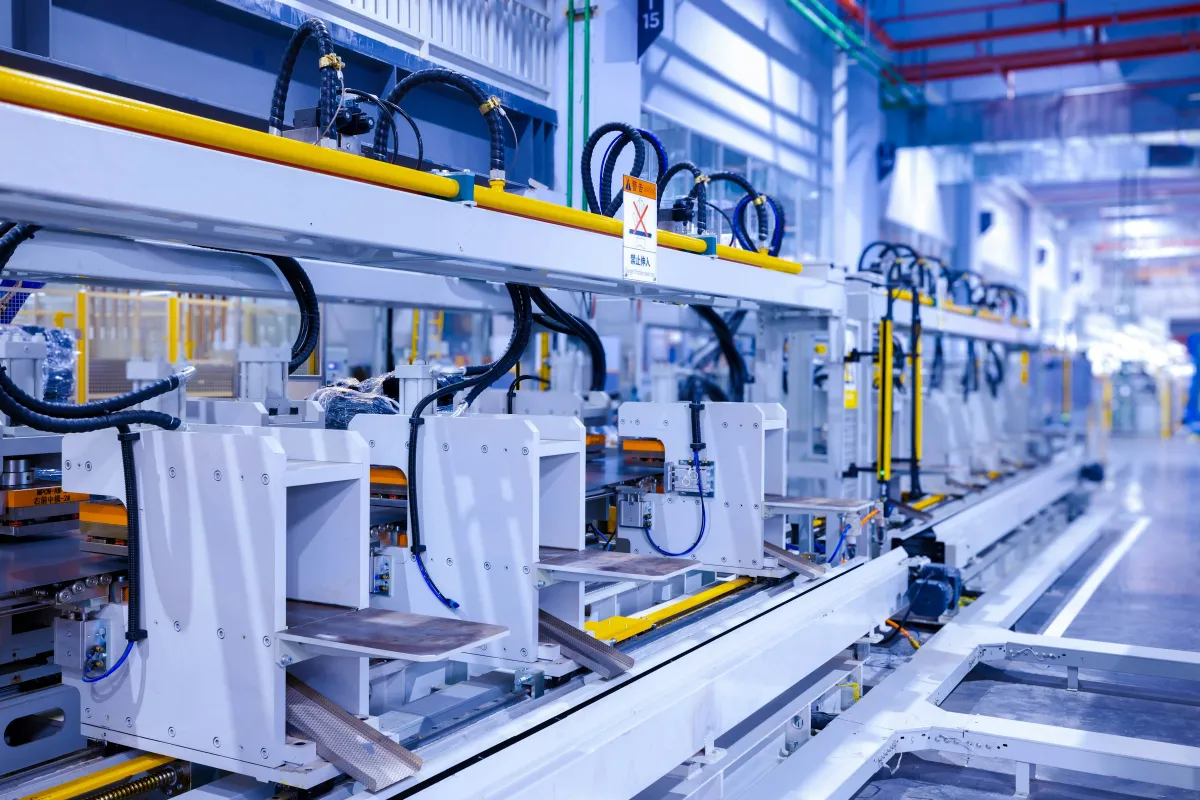
Production lines
Presses, injection molding, extrusion, filling, labeling, case packing, palletizing.
Rarely one invoice: providers differ on what one deal covers.
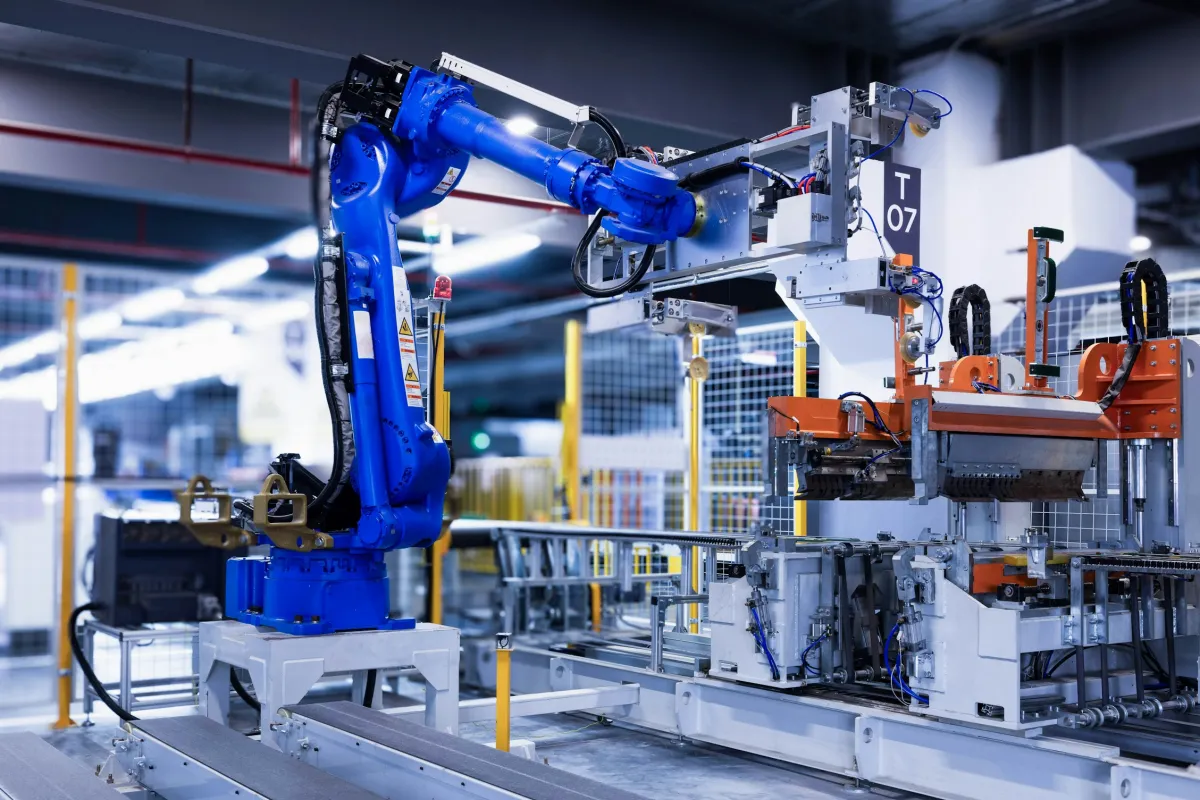
Automation and robotics
Robotic welding and assembly cells, collaborative robots (cobots), vision systems, AMRs.
A thinner resale market means more paperwork, not a refusal.
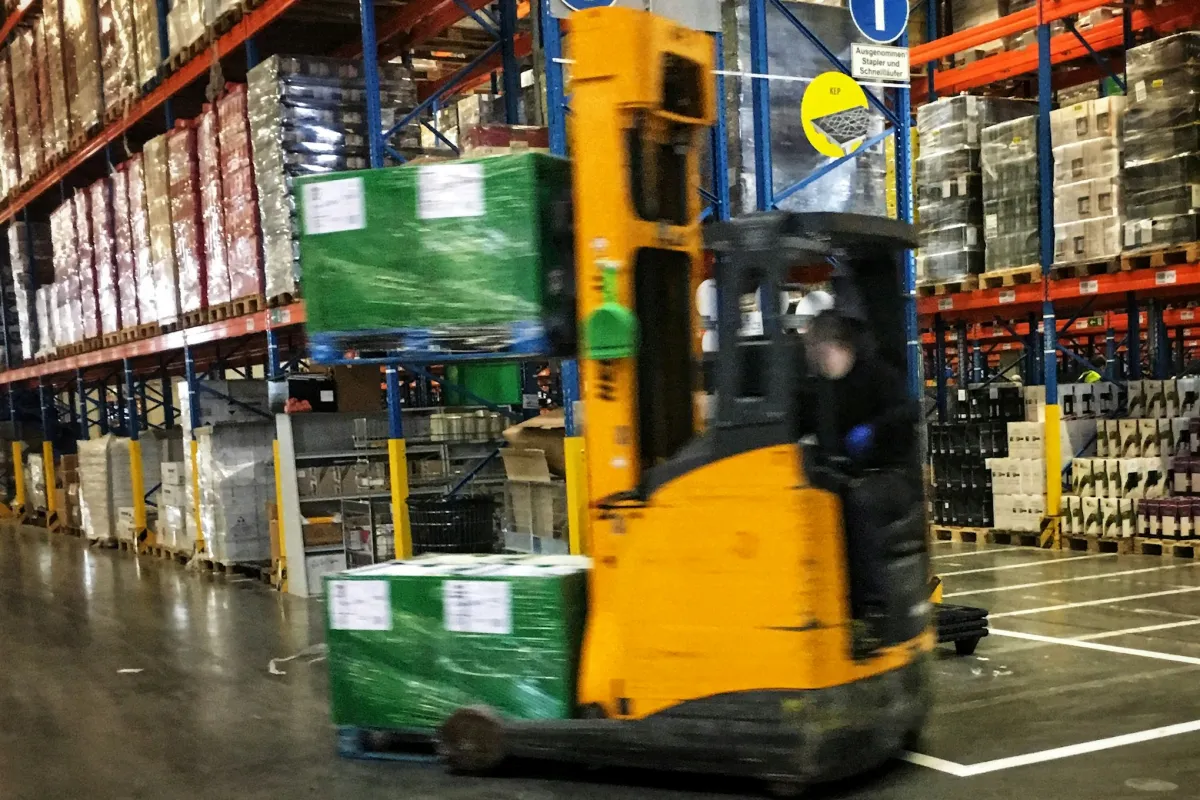
Material handling and plant
Forklifts, cranes, racking, compressors, dust collection, chillers.
Mostly common models with an active resale market.
Used machinery, dealers and plant auctions
Used machine tools are financed every day. The provider reads age, hours or cycles, condition, control generation and the market for that model.
From a dealer
The straightforward case: an invoice, a serial number and a model with a known resale value.
Often with a rebuild or warranty. The provider pays the dealer and records a lien.
Private-party
Narrows the field: some providers restrict private-party sales, and the rest add steps before they fund.
Expect: an appraisal or inspection, a lien search, and funds paid to the seller.
Plant auctions
A closing plant usually settles its auction within days, so arrange the approval before you bid. The hammer price excludes:
- The buyer's premium and any retrofit
- De-installation, rigging and freight
Rigging, installation and the first payment
This is where two offers that look identical stop being identical, because a machine tool does not arrive and start working.
From dock to first good part
Freight, rigging, a crane, floor work, an electrical drop and sometimes three-phase power, air, coolant, a foundation, software, commissioning and training.
Get the vendor's lead time in writing: a machine built to order can be months out.
Ask every provider
Does your amount financed include freight, rigging and installation? Some include it all, some only the equipment line, some only if the rigger invoices through the vendor.
A lower payment is no bargain if you then pay the rigger out of operating cash.
Match the production cycle
Your cash goes out long before your customer pays. Ask if the first payment can start at commissioning, and test it in the equipment financing calculator.
Tax: Section 179 or bonus depreciation may apply. Consult your tax advisor.
Worked example
Illustrative example, not an offer.
A fabrication shop buys a turning center at the auction of a closing plant, and has to get it onto its own floor.
- A used CNC turning center, bought at a plant auctionEquipment financing, approved before the sale$180,000
- De-installation, rigging, freight and commissioningIncluded in the amount financed by one provider, excluded by another$35,000
Amounts, rates, fees and schedules are set by the funding provider that makes the offer and are disclosed in that provider's agreement.
Decisions from some providers the same day, depending on the provider. Subject to provider approval and document turnaround.
What you need to apply
Some providers consider applications at these minimums.
- time in business
- 12 months
- monthly revenue
- $15K
- credit considered from
- 525
- bank statements
- 3 months
Meeting a minimum does not guarantee an offer.
Bring, on top of the statements
- The vendor quote, with the model and serial number
- The rigging and installation estimate
- The contract or purchase order it is for
- A government ID
Larger tickets add tax returns, financial statements and receivables aging: how much business financing you can get explains why. Capital Gurus does not make the credit decision and does not fund the transaction; the provider that makes your offer does both.
Where this fits, and where it does not
It fits
- The machine, and what it takes to make it run
- Used, from a dealer, a private seller or an auction
- A multi-year asset, kept apart from a sixty-day materials gap
It does not fit
- Steel, resin or parts bought before the job: a business term loan or line of credit
- The invoice you wait on afterwards: invoice factoring, at the back
Frequently asked questions
In short
Manufacturing equipment financing ties the deal to the machine. A provider in our network pays the vendor, records a lien on the machining center, press or line, and collects on a schedule. Some providers consider up to $500K on the application alone, and up to $5M with full documentation, depending on the funding provider.
How much can a shop finance for a machine?
Some providers consider up to $500K on the application alone, and up to $5M with full documentation, depending on the funding provider. The split is about documentation rather than about the machine: an application-only file is reviewed on statements, while the larger exercise asks for tax returns, financial statements and receivables ageing. Meeting a minimum does not guarantee an offer.
Does the financing cover rigging and installation?
Sometimes. Some providers include freight, rigging, millwright work and commissioning in the amount financed; others fund only the machine on the invoice and leave the soft costs to you. It is the single biggest difference between two offers that look alike on the quote, so ask the question before you compare the payments.
Can used or auction-bought machinery be financed?
Often, and it narrows the field. Dealers are straightforward. Private-party and plant-auction purchases are restricted by some providers, and most of the rest want an appraisal or an inspection on an older machine. Arrange the approval before the sale, because an auction settles in days and a provider cannot pay for a lot it has not seen.
Can the first payment wait until the machine is running?
Ask. Some providers in our network offer a deferred start or interim funding while a machine is being built, shipped and commissioned, which matters when a line takes months to install. It is not universal and it is not free; the structure and any charge for it are set by the provider and written into the financing agreement.
Does a long production cycle hurt the application?
Not by itself, but it has to be visible. Providers read statements and see cash leaving for materials and labor long before a deposit arrives. What they look for is a pattern that repeats. Say how long your cycle runs and ask that the first payment be set against when the work invoices rather than against the calendar.
Is financed machinery tax deductible?
Financed equipment may qualify for a depreciation deduction, including Section 179 or bonus depreciation, and the cost of funds may be treated differently again. What applies depends on your entity, your tax year, the asset and when it was placed in service. Nothing on this page is tax advice — consult your tax advisor.
Still have a question?
talk to a funding advisorCapital Gurus is not a lender. Rates, fees and terms are set by the funding provider and disclosed in your agreement. Capital Gurus · 1700 S Pavilion Center Dr, Ste 420, Las Vegas, NV 89135.
Nothing on this page is financial, legal or tax advice.
Get the next machine on your floor: see which equipment offers fit your shop.
about 5 minutes, soft credit pull only · talk to a funding advisor