
Restaurant Cash Advance: How a Merchant Cash Advance Works on Card Sales
A purchase of future card sales, not a loan. The provider collects a fixed payback from settlements.
Soft credit pull only, no obligation
Rates, factor rates, fees and terms are set by the funding provider that makes your offer and are disclosed in that provider's agreement. Figures on this page are illustrative ranges from providers in our network, not offers. A merchant cash advance is not a loan and is not priced with an interest rate; no interest is charged.
- Same-day decisions
- from some providers
- Subject to provider approval and document turnaround.
- 700+
- industries served
- Reviews
This page is part of our guide to financing for restaurants and applies the general rules of a merchant cash advance to restaurants, cafés and food-service businesses that take most of their sales on cards.
How an advance works when the sales come in on cards
The provider buys part of the card sales your restaurant has not made yet, and collects it as they arrive.
Send the statements
Bank statements, plus card-processing statements for a holdback.
Sales are read
Settlements and deposits in every month, slow ones too, and any advance remitting.
The funds land
In the business account, not with a vendor, once you sign the provider's agreement.
Remittance
Collected daily or weekly until the payback amount is reached.
Card settlements carry the file
Card sales land daily, so a provider can see the revenue it buys and collect against it. That is why modest credit with steady settlements often reads well. Weak months and negative balance days weigh more than the score.
A purchase, not a loan
A purchase of future receivables, not a promissory note, priced with a factor rate fixed at signing, not an interest rate. No maturity date: remittance runs to the payback amount. Want an offer read with you? Talk to a funding advisor.
What restaurants use an advance for
Short, urgent needs that the next weeks of sales will pay for.
A repair that stops service
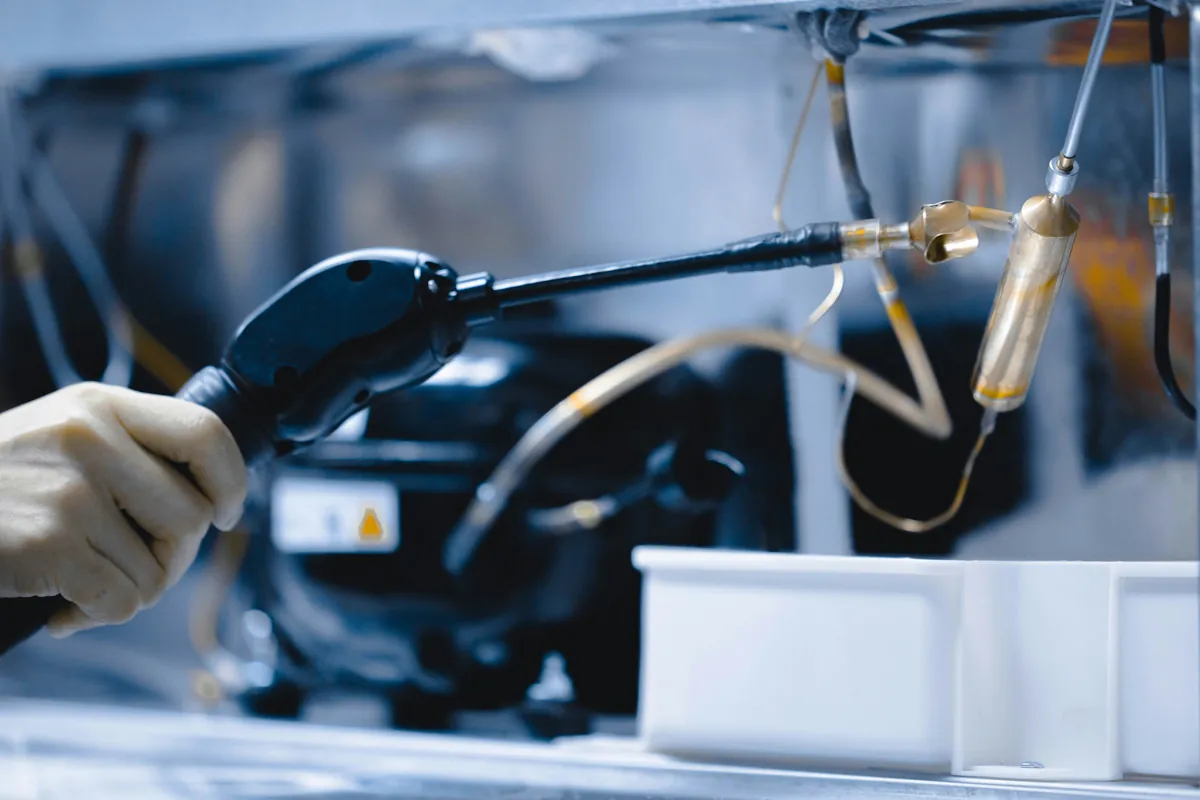
A walk-in compressor, a hood fan, a dish machine or a fryer that fails before the weekend.
Replacing the whole unit usually costs less as equipment financing.
Stock for a busy stretch
Food, beverage and supplies ordered ahead of a holiday, a festival or a large booking.
It fits when the bookings that will use the stock are already in.
The quiet weeks
Payroll and rent through a short dip in covers, with the busy season weeks away.
A dip that returns every year suits a line of credit better.
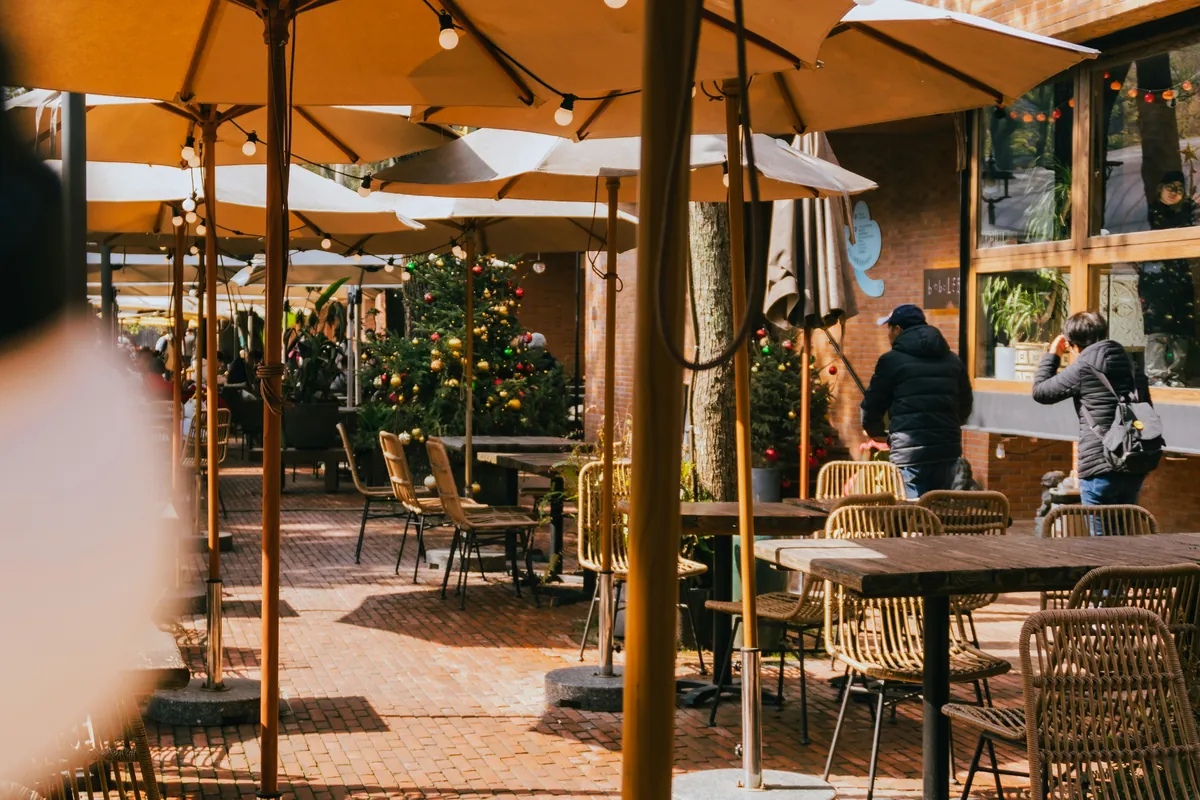
The patio and holidays
Heaters, umbrellas, extra staff and décor to open the outdoor tables for a season.
Spent where the extra covers will pay the remittance.
How the payback is collected from a restaurant
The agreement names the method. Ask which one before you compare offers.
A holdback on card settlements
An agreed share of each day's card sales is held back, through your processor or a split of the deposit.
Falls on a slow Tuesday and rises on a full Saturday, which suits a seasonal dining room.
A fixed daily ACH
The same amount leaves the business account every business day, whatever the covers.
Easy to budget, but the debit is the same on a quiet day as on a full one.
A fixed weekly ACH
One larger fixed debit a week from the business account, with a week of sales between them.
Ask whether a temporary adjustment is possible if sales fall.
Worked example
Illustrative example, not an offer.
A single-location restaurant that takes most of its sales on cards loses its walk-in compressor two weeks before the holiday bookings, and needs the repair and the holiday stock at once. The provider collects an agreed share of daily card settlements until the payback amount is reached.
- The compressor repair and the holiday stockFunded amount, paid into the business account$30,000
- The payback amount, fixed at signingCollected as a holdback on card settlements$39,000
- The cost of the advancePayback amount less funded amount; it does not move after signing$9,000
Factor rates, fees and remittance are set by the funding provider that makes each offer and are disclosed in that provider's agreement. A merchant cash advance is not a loan and no interest is charged.
Decisions from some providers the same day, depending on the provider. Subject to provider approval and document turnaround.
What you need to apply
Some providers consider applications at these minimums.
- time in business
- 12 months
- monthly revenue
- $15K
- credit considered from
- 525
- bank statements plus ID
- 3 months
Meeting a minimum does not guarantee an offer.
Bring, on top of the statements
- Your card-processing statements for the same months
- The balance and remittance of any advance still running
- The lease on your premises, with the term left on it
Some providers exclude single-location bars and a few restrict food service, so say how much of your revenue is alcohol: we send the file only to providers whose guidelines accept it.
Where an advance fits, and where it does not
It fits
- A repair that stops service: paid for by the sales it brings back
- Stock for bookings already in the diary: a short need with the revenue in sight
It does not fit
- A new walk-in or hood: equipment financing usually costs less
- A dip every winter: a line of credit fits
- A second site: a long-term project
Frequently asked questions
In short
A restaurant cash advance is a purchase of future receivables, not a loan: a provider pays a lump sum and collects a fixed payback amount from card settlements. Cost is a factor rate, not an interest rate. Advances from $10K–$500K are considered, depending on the funding provider, with same-day decisions from some, subject to provider approval and document turnaround.
Is a restaurant cash advance a loan?
No. A merchant cash advance is the purchase of a fixed amount of your restaurant's future receivables, documented as a purchase agreement rather than a promissory note. The provider pays a funded amount now and collects an agreed payback amount from your card settlements or deposits. The price is a factor rate, not an interest rate, and no interest is charged.
How much can a restaurant get from a cash advance?
Advances from $10K–$500K are considered across the network, depending on the funding provider. Where a restaurant lands in that range follows its monthly card settlements and deposits, how steady they stay through the slow months, and what is already remitting to other providers. Ask for what the need costs rather than the largest figure on offer: providers can read an inflated request as a weak one.
How fast can a restaurant get an advance for an emergency repair?
Some providers in our network give same-day decisions, subject to provider approval and document turnaround. Once approved, most businesses receive funds within 1–3 business days; some fund in as little as 6 hours. What slows a restaurant file down is usually the paperwork: missing months, card-processing statements left out, or an advance nobody mentioned. Send complete months, every page, and name every position on the application, so the only wait left is the provider's.
Do providers give cash advances to bars?
Some do. A standalone, single-location bar is excluded by some providers in our network, so a bar's file reaches a narrower panel than a restaurant's. What widens it is a real food mix in the card settlements, a second location or a longer trading history. Say how much of the revenue is alcohol on the application, so the file goes only to providers that accept it.
What happens to the remittance in a slow month?
It depends on the method. A holdback on card settlements falls with sales, because it is a share of what comes in, and agreements tied to sales usually carry a reconciliation clause. A fixed daily or weekly ACH does not fall on its own: contact the provider before a remittance is missed, since some allow a temporary adjustment. What happens on default is set out in your agreement.
Can I get a second advance while one is still remitting?
Sometimes, but read the first agreement before you ask. An advance already remitting reduces what a new provider will fund, some providers decline stacked files outright, and two remittances come out of the same card settlements every day. If several positions are straining the account, some providers in our network can consolidate them into a single remittance schedule.
Still have a question?
talk to a funding advisorKeep reading
Related pages
BlogKeep the kitchen running: see which advance offers fit your restaurant.
about 5 minutes, soft credit pull only · talk to a funding advisor